


Does New CFO Hire Change The Bull Case For Teladoc Health Stock?
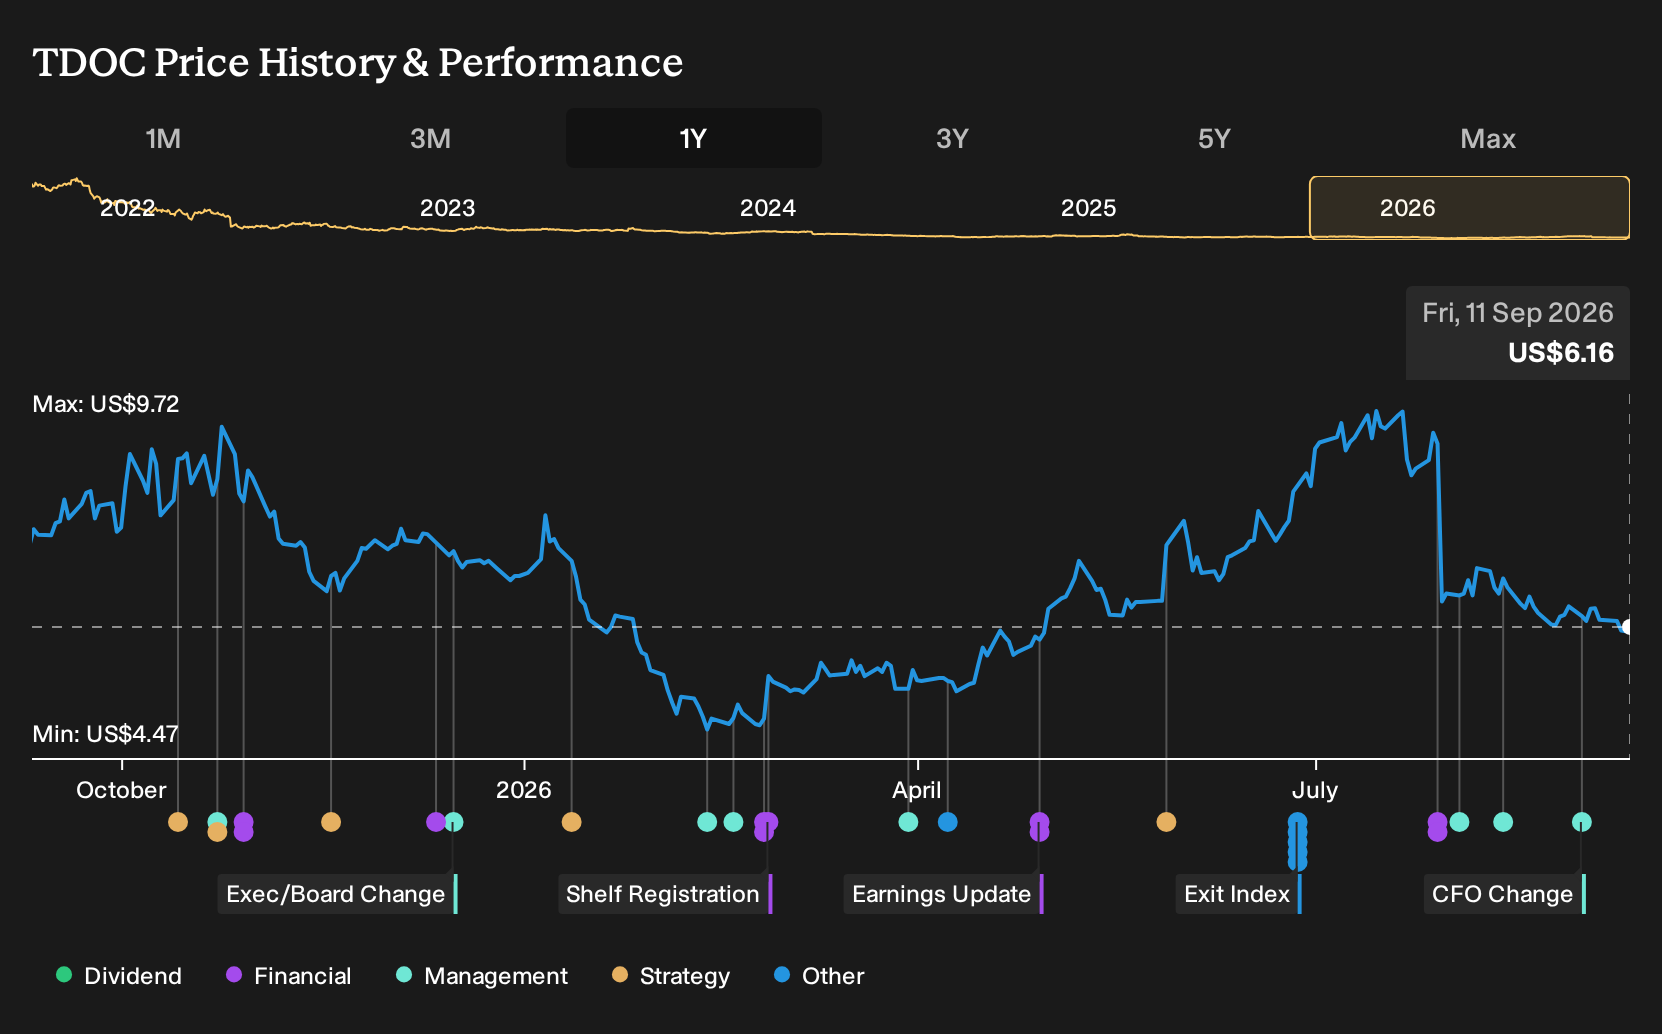
- Teladoc Health appointed Michael Grasher as Chief Financial Officer on 31 August 2026, adding more than 30 years of insurance and financial services experience, including multiple public company CFO roles.
- Grasher’s mix of insurance-focused finance leadership, equity research background, and enterprise efficiency work gives Teladoc Health a CFO with deep experience in capital allocation, reporting rigor, and cost discipline at a time of ongoing profitability pressure.
- We will look at how Teladoc Health's investment narrative is affected by this CFO appointment and his insurance sector expertise.
Scan how Teladoc Health’s CFO change compares with other potential turnaround stories and efficiency plays by reviewing our curated list of 16 high quality undiscovered gems in similar situations.
Teladoc Health Investment Narrative Recap
To own Teladoc Health, you need to believe virtual care can support steady demand across chronic care, mental health and international markets, even with intense competition. In the near term, the key question is whether management can stabilise BetterHelp and maintain Integrated Care contracts while keeping revenue roughly flat and working toward smaller losses.
The new CFO appointment looks more operational than thesis changing. A finance chief with deep insurance and capital allocation experience can influence cost discipline and reporting quality, which connects directly to the key short term catalyst: clearer progress on profitability. The largest risk still sits with BetterHelp churn, pricing pressure and a lower margin insurance mix.
The Michael Grasher hire is the clearest recent signal that Teladoc Health is trying to match its capital structure and cost base to a slower growth, profitability focused phase. His background in insurance led businesses and equity research aligns closely with Teladoc’s current reality of margin pressure, flat revenue expectations and scrutiny on cash use.
For you as a shareholder, the real test is whether Grasher can tighten expense control without limiting product investment in chronic care and BetterHelp. Execution on insurance based mental health, integration of past deals and management of higher risk funding sources all run through the finance office. CFO decisions could therefore shape how quickly Teladoc Health moves from losses toward a more sustainable earnings profile.
Teladoc Health Earnings Path Embedded In Analyst Models
On current analyst assumptions, Teladoc Health's long term story leans heavily on margins, not rapid top line expansion. Consensus expects revenue to stay broadly flat over the next three years, while the profit margin is modelled to shift from a loss of 6.8% to a positive 6.7% by 2029. This feeds directly into how investors might judge the CFO's room to manoeuvre.
That margin swing underpins a sizeable move in the earnings line. Analysts are working with current earnings of a loss of US$171.1 million and an outlook for US$172.9 million of profit by 2029. The shift required to get there is an earnings improvement of about US$344 million from today, which gives a rough sense of how much efficiency and mix change would need to come through the income statement.
These same estimates assume Teladoc Health's share count climbs by around 2.16% a year for the next three years. For existing investors, that projected issuance matters because it can dilute per share outcomes, even if the absolute profit figure reaches the US$172.9 million mark outlined in the analyst work.
The valuation framework in the consensus work builds on those operating assumptions. It anchors on Teladoc Health generating US$2.6b of revenue and US$172.9 million of earnings by 2029, with the equity trading on a forward P/E of 11.7x at that point, compared with a current multiple of 9.1x on loss making earnings. That P/E level is well below the 31.7x applied to the broader US Healthcare Services peer group in the same source.
On price targets, the analyst group sits in a fairly tight range. The average target sits at US$7.97 a share, against a current price of US$8.66, with individual views stretching from US$5.00 at the low end to US$11.00 at the high end. That 8.6% gap between the market price and the consensus target suggests many professionals see the stock as roughly fairly valued on their 2029 margin and earnings framework. This puts more weight on whether Teladoc Health and its new CFO can deliver the cost and mix shifts those numbers assume.
Teladoc Health's narrative projects US$2.6b revenue and US$172.9 million earnings by 2029. This requires broadly flat yearly revenue and an earnings improvement of about US$344 million from a current loss of US$171.1 million.
Uncover why Teladoc Health's fair value indicates a 29% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For Teladoc Health, the biggest swing factor in the more bearish narrative is revenue pressure. The lowest analysts were modeling revenue slipping about 3.1% a year and earnings moving from a loss of US$177.4 million to US$168.6 million profit by 2029. Those pre announcement views could shift if you think a new CFO materially changes the cost and reimbursement story. It makes sense to compare several viewpoints before deciding where you land.
Explore 3 other Teladoc Health fair value estimates, including one that suggests it could be worth just $7.97!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Teladoc Health research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Teladoc Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teladoc Health's overall financial health at a glance.
Looking For More Investment Ideas Beyond Teladoc Health?
If the Teladoc Health story has you thinking about where efficiency, balance sheet strength and dependable cash flows could matter next, it can help to scan a wider set of companies that share some of those traits.
- For investors who care about quality and value working together, start with a curated pool of 31 high quality undervalued stocks that pair solid fundamentals with discounts to their underlying metrics.
- If balance sheet resilience ranks high on your checklist, focus on companies in our list of solid balance sheet and fundamentals (23 results) to see which businesses keep debt and liquidity firmly under control.
- For a more defensive tilt that still targets income, filter for businesses in the 6 dividend fortresses to see where higher yields coincide with more robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com