


UniFirst (UNF) Launches Always U As Investors Ask If The Stock Is Fully Valued
Why UniFirst’s Always U launch matters for shareholders
UniFirst (UNF) just rolled out its Always U workwear collection, a new line built around comfort, mobility, and dedicated women’s fits, giving investors fresh insight into how management is thinking about product design and customer needs.
Recent trading reflects that story in the numbers. UniFirst’s share price is up 41.87% year to date, and the 1-year total shareholder return of 61.08% suggests strong momentum. However, the 30-day share price return of 5.29% indicates some cooling after that run.
Scan for more workwear and industrial suppliers that could be benefiting from similar trends in comfort and inclusivity by reviewing our curated list of list of solid balance sheet and fundamentals (23 results).
After a 61.08% 1-year total return and a recent 5.29% gain over 30 days, UniFirst now trades near its US$273.33 price target. Does that create a more attractive entry point by waiting, or by paying the current price today?
Most Popular Narrative: 1.5% Undervalued
UniFirst’s most followed narrative pins fair value at $279, only slightly above the last close of $274.68, which frames the Always U launch inside a tight valuation gap.
Significant investments in technology, specifically an ERP system, are anticipated to enhance efficiency, leading to improved profitability and reduced operational costs once fully implemented, which should impact net margins positively in the long run.
Read the complete narrative. Read the complete narrative.
Want to see what justifies that fair value so close to today’s price? The narrative leans on measured revenue gains, margin uplift, and a premium future earnings multiple. The exact mix of growth, profitability and discount rate assumptions may surprise you.
Result: Fair Value of $279 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, UniFirst’s story can change fast if wearer levels keep softening or if health care expenses climb further and eat into those carefully modelled margins.
Find out about the key risks to this UniFirst narrative.
Another View: UniFirst looks expensive on earnings multiples
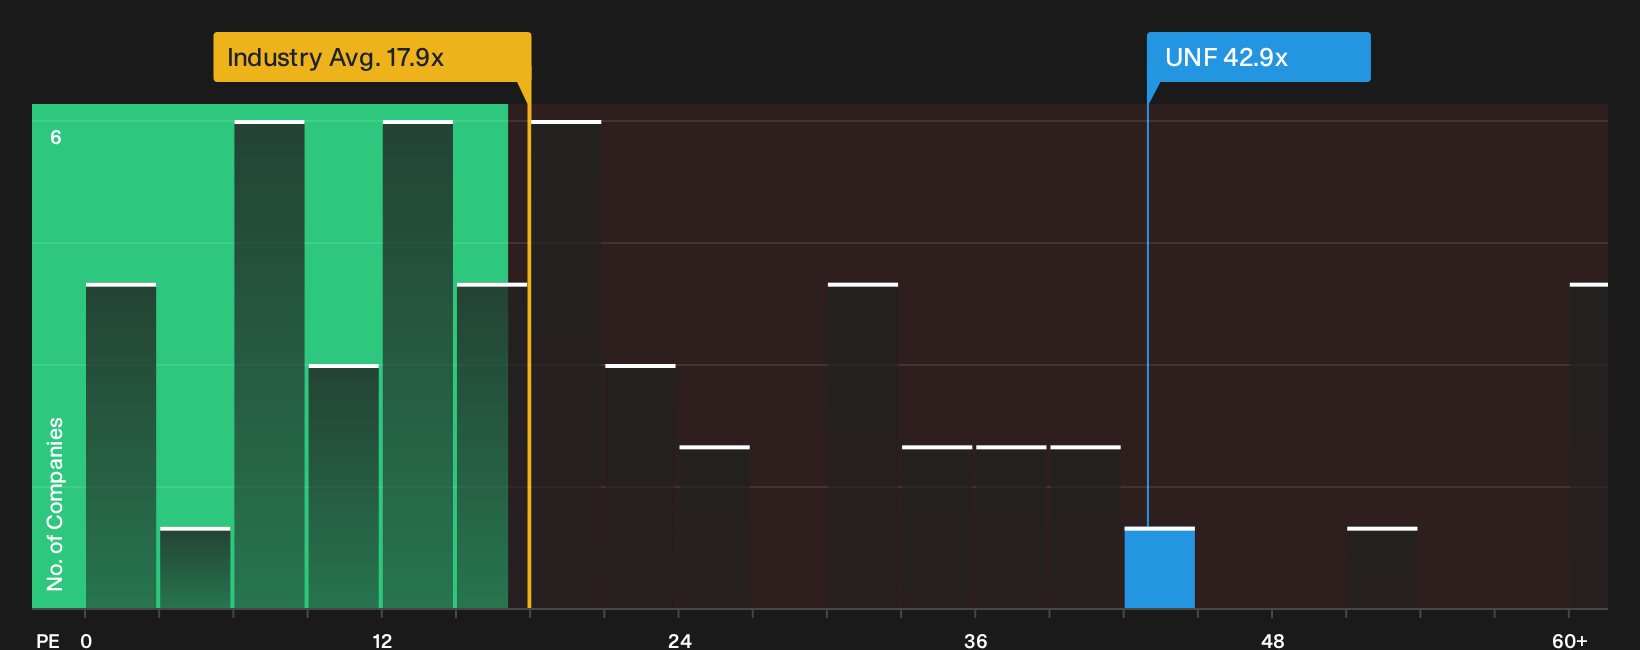
The SWS DCF model sees UniFirst as 1.5% undervalued, yet its P/E ratio of 42.9x tells a different story. That multiple is more than double the US Commercial Services industry average of 18.3x and well above peers at 26.4x. It also sits far above a fair ratio of 22.8x, which hints at meaningful valuation risk if sentiment cools.
For a closer look at how that gap could close over time, including what the fair ratio implies if the market reprices UniFirst on more typical earnings multiples, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
With sentiment on UniFirst split between a tight fair value range and a rich P/E, it may help to review the full picture yourself and then act before the next narrative shift takes hold by reviewing the 1 key reward.
Looking for more investment ideas beyond UniFirst?
Do not stop with UniFirst. Broaden your watchlist now and give yourself more options before the next big move shows up in the headlines.
- Target long term compounding potential by focusing on quality businesses trading below estimated worth through the 31 high quality undervalued stocks.
- Prioritise resilience in your portfolio by scanning for 11 resilient stocks with low risk scores that aim to limit downside when volatility picks up.
- Hunt for future leaders early by reviewing 16 high quality undiscovered gems that pair solid fundamentals with limited current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com