


Is National Fuel Gas (NFG) Stock Stretched Or Still Reasonable?
National Fuel Gas stock has delivered a strong 84.9% total return over the past five years, yet both an intrinsic value estimate using a Discounted Cash Flow method and market multiples currently point to the shares trading below what the underlying cash flows may justify. The market is pricing the stock at about US$81.00 after a softer past year, which contrasts with valuation checks that lean toward a discount rather than a premium.
- Over five years, a total return of 84.9% suggests National Fuel Gas has already rewarded patient holders, yet the current pricing still screens as cheap on long term value grounds.
- Future cash generation from the utility and pipeline businesses can support the current valuation, while any sustained pressure on commodity sensitive earnings or large capital spending needs may weigh on how much of that cash ultimately reaches shareholders.
- The broader valuation checks, including earnings based multiples and the Discounted Cash Flow intrinsic estimate, indicate National Fuel Gas screens as undervalued in most tests, with a high value score that points to a meaningful discount to estimated worth.
For investors, the debate is whether that apparent discount to intrinsic value offers a margin of safety or simply reflects the risks already built into National Fuel Gas at around US$81.00 per share.
Spot opportunities beyond National Fuel Gas by scanning a curated list of value focused stocks in the 31 high quality undervalued stocks.Is National Fuel Gas a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash National Fuel Gas can reasonably be expected to generate for shareholders over time. Latest twelve month free cash flow sits at about $177.8 million, with projections assuming that cash generation grows from this base rather than shrinking. That pattern supports a 2 stage Free Cash Flow to Equity framework, which is better suited to a mature utility and pipeline group than a hyper growth story.
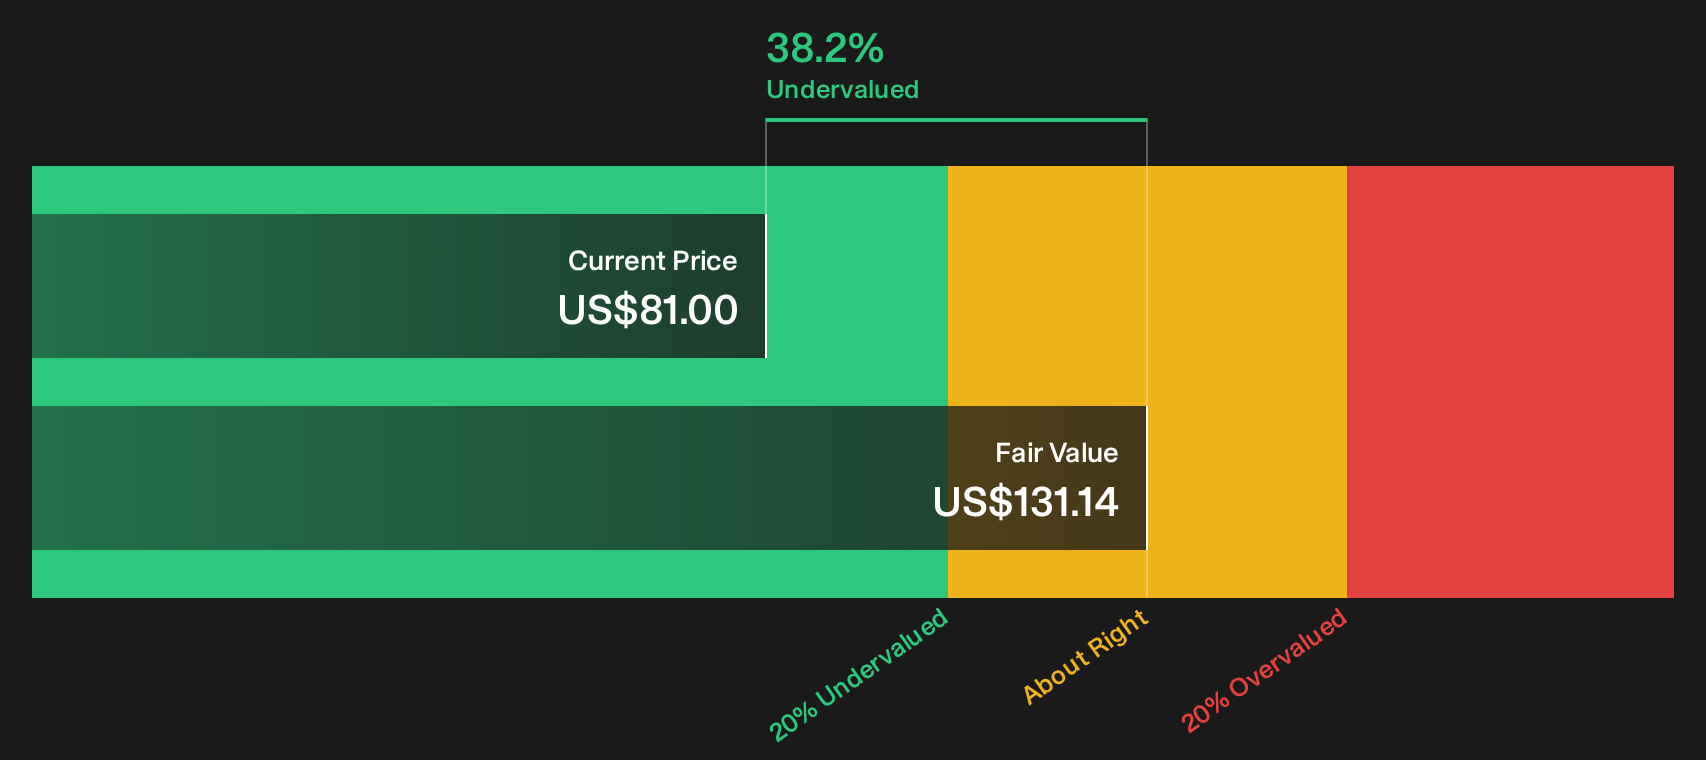
On those assumptions, the DCF model points to an estimated intrinsic value of about $131 per share, compared with a current price near $81. The implied 38.2% discount means the market valuation does not fully reflect the projected cash flows using these inputs, even after accounting for the capital spending and commodity exposed parts of National Fuel Gas.
Taken together, the DCF work suggests National Fuel Gas screens as undervalued relative to what its projected cash flows might support.
Our Discounted Cash Flow (DCF) analysis suggests National Fuel Gas is undervalued by 38.2%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Is National Fuel Gas Still Cheap on Earnings?
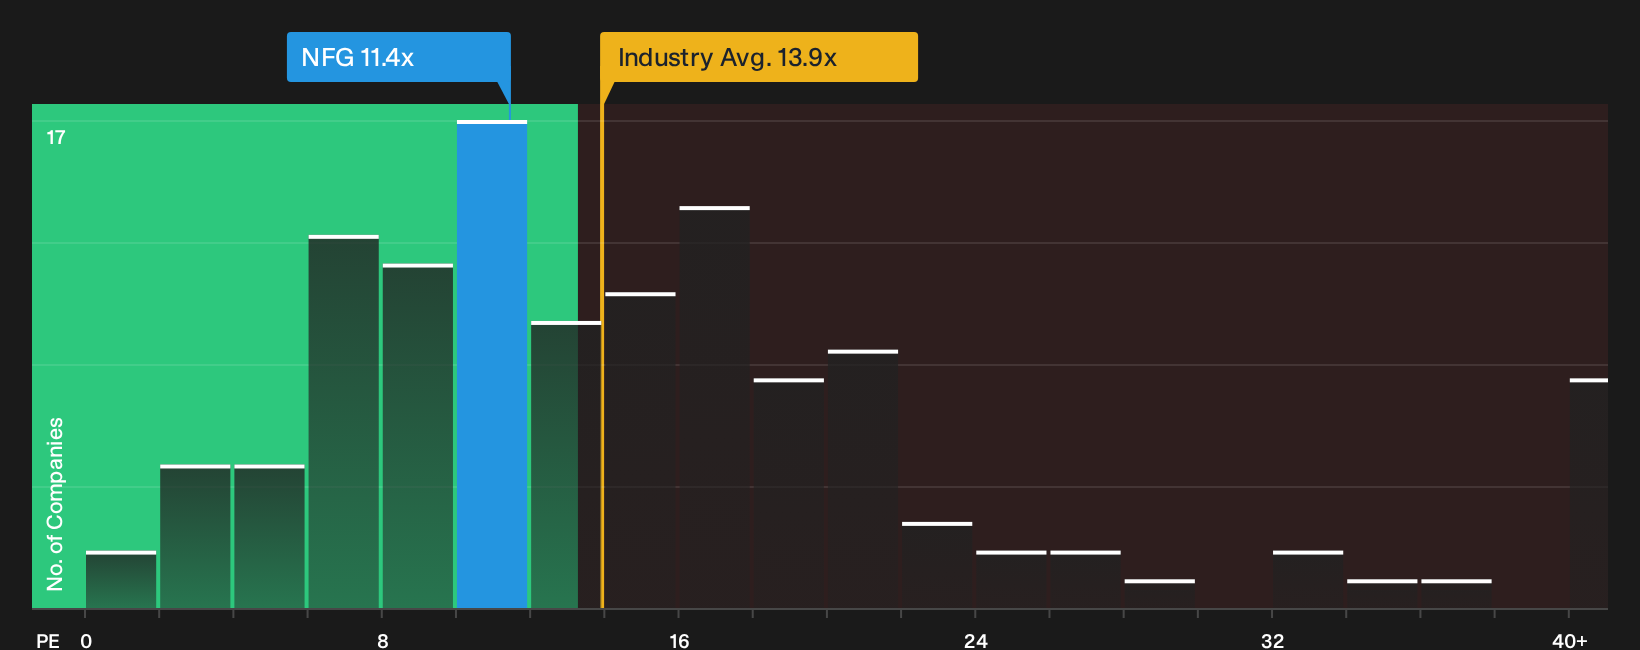
P/E works well for National Fuel Gas because earnings play a central role in how investors usually frame returns for regulated utilities and pipeline operators. The stock currently trades at a P/E of about 11.4x, which is below both the Gas Utilities industry average of roughly 13.9x and a peer group near 15.3x.
A tailored fair P/E ratio for National Fuel Gas, based on its risk profile and profitability assumptions, is estimated at about 18.7x. That is a wide gap relative to the present 11.4x multiple, so the shares appear to trade at a discount even when compared with a company-specific benchmark rather than just sector averages.
On earnings multiples alone, National Fuel Gas appears undervalued compared with both its industry and a more customised fair P/E benchmark.
See what the numbers say about this price — find out in our valuation breakdown.
The National Fuel Gas Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for National Fuel Gas give you a clear bridge from the valuation puzzle above to the assumptions that sit underneath it. Instead of a single fair value output, Narratives spell out the kind of future on growth, margins and earnings that would need to play out for National Fuel Gas' share price to be materially higher or lower than it is today. Where a ratio or model offers one headline figure, Narratives unpack the future story that figure relies on so you can watch in real time whether management and the market are actually moving in that direction. These are available on Simply Wall St's Community page and turn the numbers into specific business outcomes that can be monitored over time.
Add your own narrative on National Fuel Gas' path for growth, margins, and execution so your number-driven view is on record as fresh data arrives. Share a thesis, highlight the key drivers you think matter most, and see how your perspective compares with future results and market reactions.
Do you think there's more to the story for National Fuel Gas? Head over to our Community to see what others are saying!
The Bottom Line
National Fuel Gas screens as undervalued on both the Discounted Cash Flow (DCF) intrinsic value estimate and on earnings based multiples, which is a rare alignment. The DCF work suggests the present share price does not fully reflect the cash the utility and pipeline operations are modeled to generate, while the P/E gap points to a cautious market stance rather than a stretched valuation. The key question from here is whether future cash generation and earnings hold up well enough for that discount to close, or whether ongoing commodity exposure and capital needs keep the stock trading on a lower multiple.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com