


What Korea Data Center Expansion Means For Schneider Electric (ENXTPA:SU) Shareholders
- Schneider Electric has widened its reach in Korea's AI data center market as CK Solution becomes an authorized distributor of its power, cooling, and automation solutions, integrating these with CK's existing HVAC and construction capabilities.
- The arrangement gives Schneider Electric deeper access to data center build projects in Korea, linking its energy management hardware and software directly into CK Solution's design pipeline rather than relying only on standalone product sales.
- This development places Schneider Electric's investment narrative in the context of its Korean data center distribution agreement and wider digital infrastructure demand.
Explore Schneider Electric's peers that are benefiting from the same AI infrastructure trend by reviewing our hand picked list of 89 AI infrastructure stocks.
Schneider Electric Investment Narrative Recap
To own Schneider Electric, you need to be comfortable with a story built on electrification, software and data centers, and you also need to accept near term margin and capital intensity trade offs. The CK Solution deal fits cleanly into that thesis because it ties Schneider Electric more tightly to AI data center demand in Korea without changing the overall risk profile.
The key near term swing factor remains execution on high growth data center and digital services backlogs while keeping profitability intact as Systems outgrow Products. The biggest immediate risk still sits in margin pressure and debt funded investment, and this new Korean distribution agreement does not materially change that balance.
The most relevant recent development for this story is Schneider Electric presenting at the 18th Annual Boston C Level Technology Leadership Summit on 10 September 2026. The session is led by the SVP and CIO, which squarely puts digital infrastructure, software and IT centric priorities in front of large technology buyers and partners.
For you as an investor, that matters because Schneider Electric is promoting a mix of hardware, automation and recurring software for data centers, grids and buildings. Visibility with senior technology leaders can support the company’s efforts to deepen relationships around EcoStruxure, AVEVA SaaS and AI centric workloads, but the core execution risks on margins, leverage and Industrial Automation performance remain unchanged.
Schneider Electric's current analyst narrative points to revenues of €56.4b and earnings of €8.3b by 2029, based on an assumed 10.3% yearly revenue growth rate and an increase in earnings of about €3.6b from €4.7b today.
Uncover why Schneider Electric's fair value indicates a 12% potential upside to its current price that could narrow quickly.
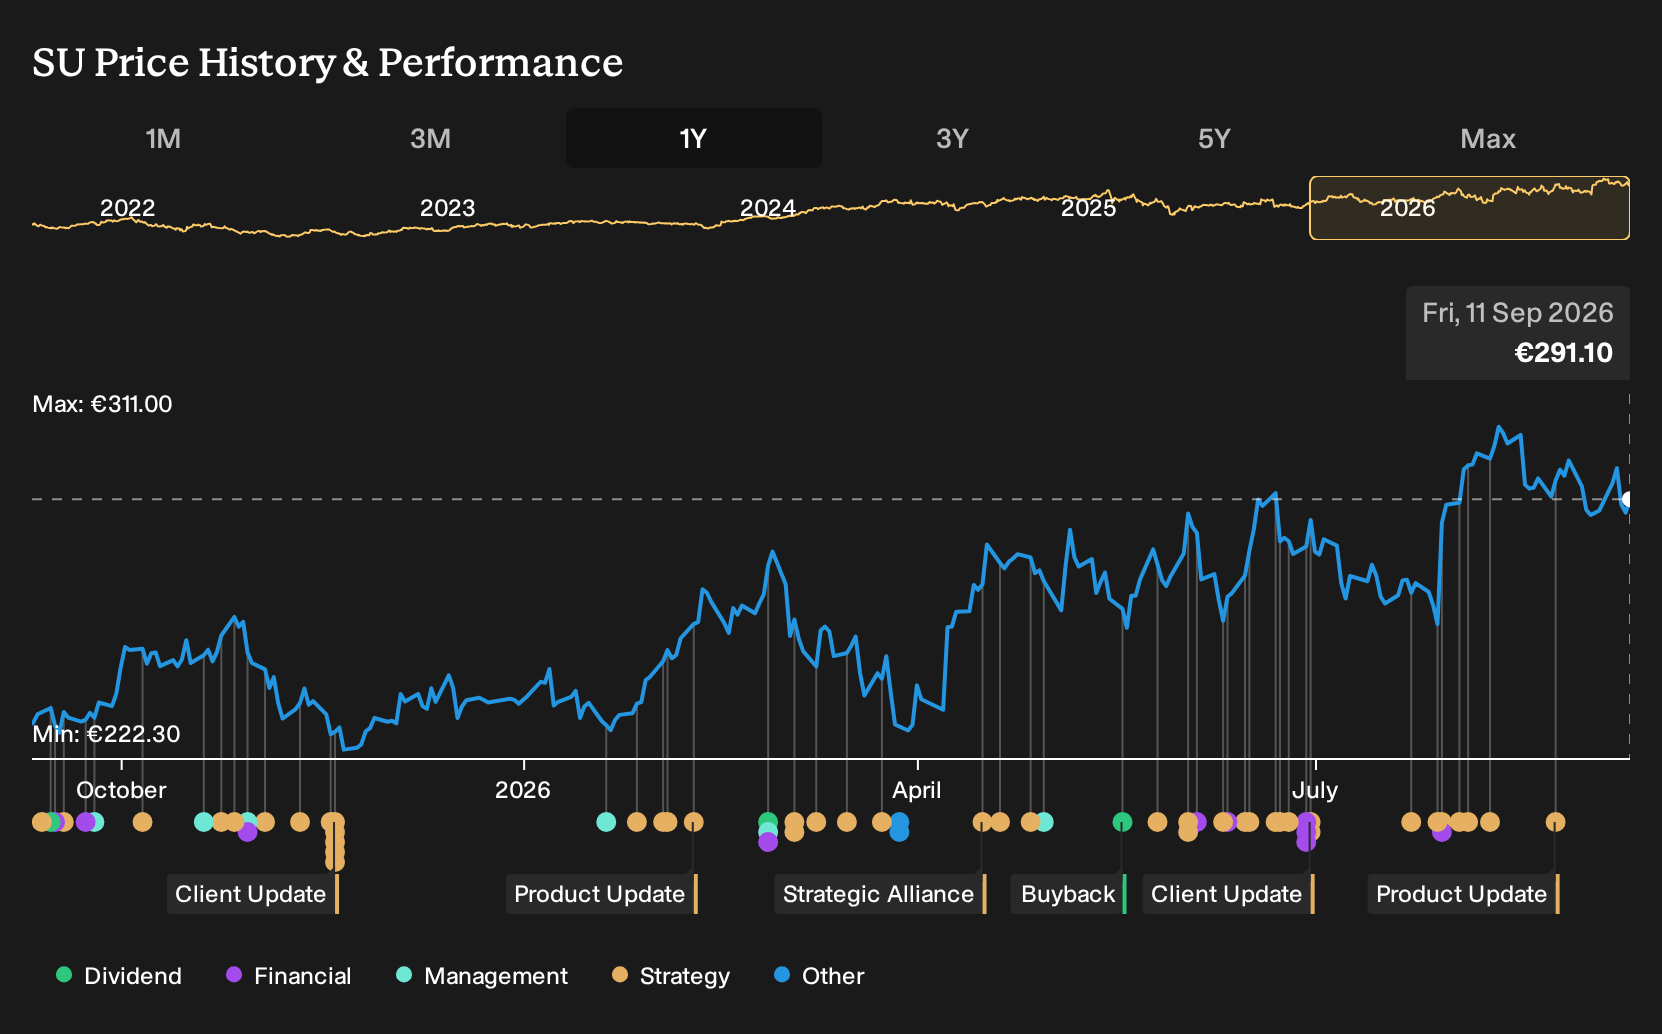
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly €219.79 to €379.32, so private investors are clearly not aligned on where Schneider Electric should trade. Those views were set before the CK Solution AI data center deal and the recent Boston summit, which could reshape expectations on margins, debt use and long term demand. Readers should treat this spread as a prompt to review multiple viewpoints before forming a stance.
Explore 3 other Schneider Electric fair value estimates, including one that suggests as much as 24% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Schneider Electric research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Schneider Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Schneider Electric's overall financial health at a glance.
Looking for more Schneider Electric style investment ideas?
If the Schneider Electric story has you thinking about how to position your portfolio around quality, risk and income, the Simply Wall St Screener can help you broaden your watchlist in a focused way.
- If capital preservation is high on your checklist, start with a set of companies that score strongly on stability and balance sheet strength through our 97 resilient stocks with low risk scores.
- If you prefer income as a core part of your returns, shortlist potential payers and assess yield alongside fundamentals by reviewing our 164 dividend fortresses.
- If you want to get in early on under followed stories with solid numbers, widen your search using our 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com