


Martin Marietta Materials (MLM) Faces Cost And Lhoist Deal Questions As Valuation Debate Builds
Event backdrop for Martin Marietta Materials
Pressure on Martin Marietta Materials (MLM) has intensified after higher operating costs, softer residential and private nonresidential demand, and a weaker sales outlook converged with investor concerns around the proposed Lhoist North America acquisition.
Over the past year, Martin Marietta Materials has seen its share price momentum cool, with the stock down 6.24% on a 30 day basis and 11.67% over 90 days. The latest 1 day share price return of 1.49% sits against a 1 year total shareholder return decline of 16.73%, but gains of 22.01% over three years and 53.43% over five years, signaling fading short term sentiment after earlier long term compounding.
Compare Martin Marietta Materials' recent pressure with other construction and materials stocks that still show resilient fundamentals using the hand picked list of solid balance sheet and fundamentals (23 results).
Martin Marietta Materials now trades well below its recent highs after concerns around costs, demand, and the Lhoist deal. Does that reset offer a reasonable entry, or does patience still look safer before the valuation work starts?
Most Popular Narrative: 23% Undervalued
With Martin Marietta Materials closing at $509.96 against a narrative fair value of $662.65, the current quote sits well below what consensus modelling implies.
The exchange of cement and ready-mix assets for high-quality aggregate operations in Virginia, Missouri, Kansas, and Vancouver, BC, strategically increases Martin Marietta's exposure to advantaged geographies with strong barriers to entry and pricing power, expected to enhance margins and support stable earnings growth over time.
Investors may want to examine what earnings path would need to unfold for that margin story to hold up. The popular narrative leans on faster top line growth, higher profits, and a richer future earnings multiple. It is important to understand which set of long-range assumptions would have to play out for Martin Marietta Materials to reach that $662.65 fair value mark.
Result: Fair Value of $662.65 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the bullish narrative around Martin Marietta Materials could be shaken if infrastructure funding softens or if higher energy and financing costs squeeze margins more than expected.
Find out about the key risks to this Martin Marietta Materials narrative.
Another View on Martin Marietta Materials' Valuation
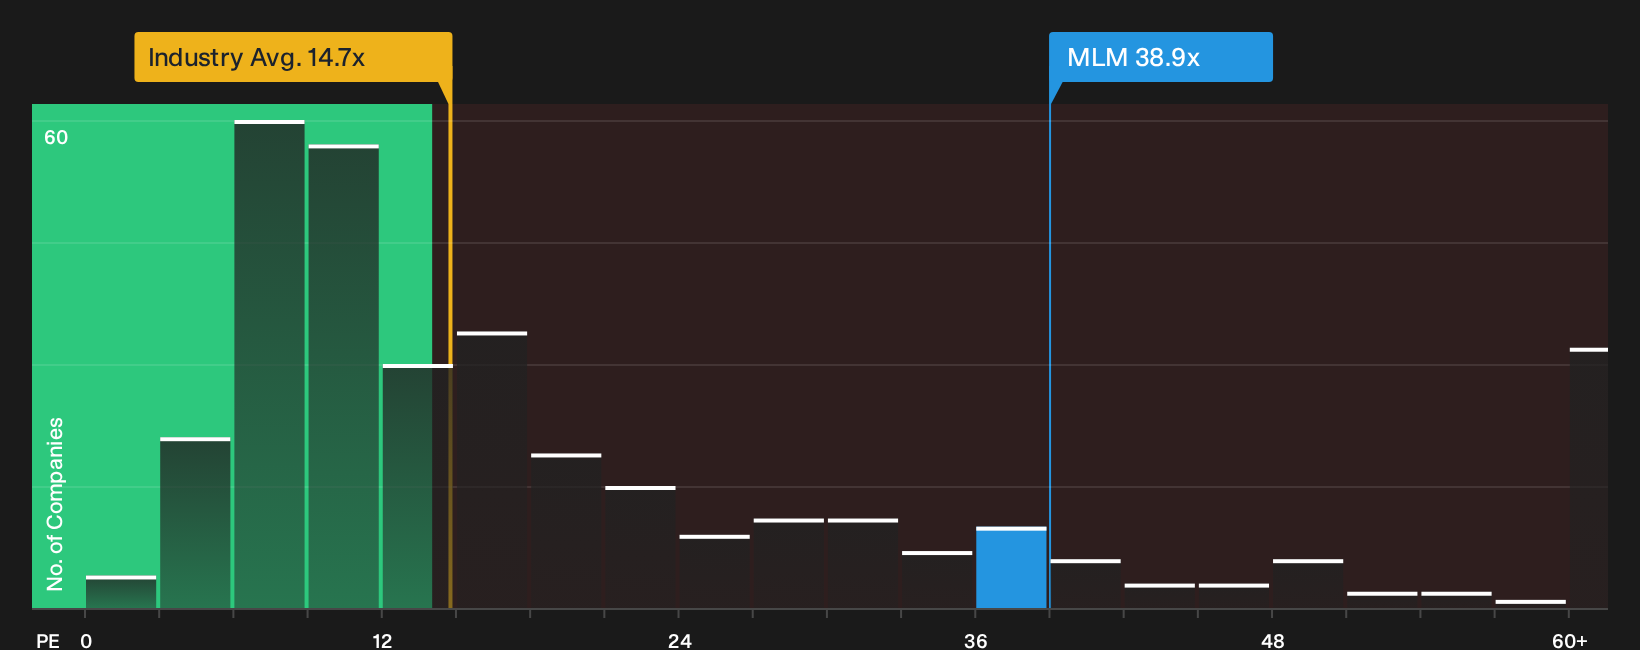
On simple earnings multiples, Martin Marietta Materials screens as expensive. The shares trade on a P/E of 38.9x versus 14.8x for the global Basic Materials group and 20.6x for peers, while the fair ratio sits at 27.4x. That gap points to higher valuation risk if sentiment cools further.
For investors who want to see how that earnings multiple stacks up against detailed valuation work, it is worth checking the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Martin Marietta Materials can feel noisy, so move quickly, review the data for yourself, and weigh both sides of the story with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Martin Marietta Materials?
If Martin Marietta Materials has your attention, do not stop here. The wider market holds plenty of other opportunities that could better match your style.
- Target potential mispricing and hunt for quality businesses trading below their implied value through the 31 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that aim to sustain generous payouts with the 6 dividend fortresses.
- Dial down portfolio risk by focusing on resilient businesses with sturdier finances using the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com