


Labor Talks Might Change The Case For Investing In Stellantis Stock (BIT:STLAM)
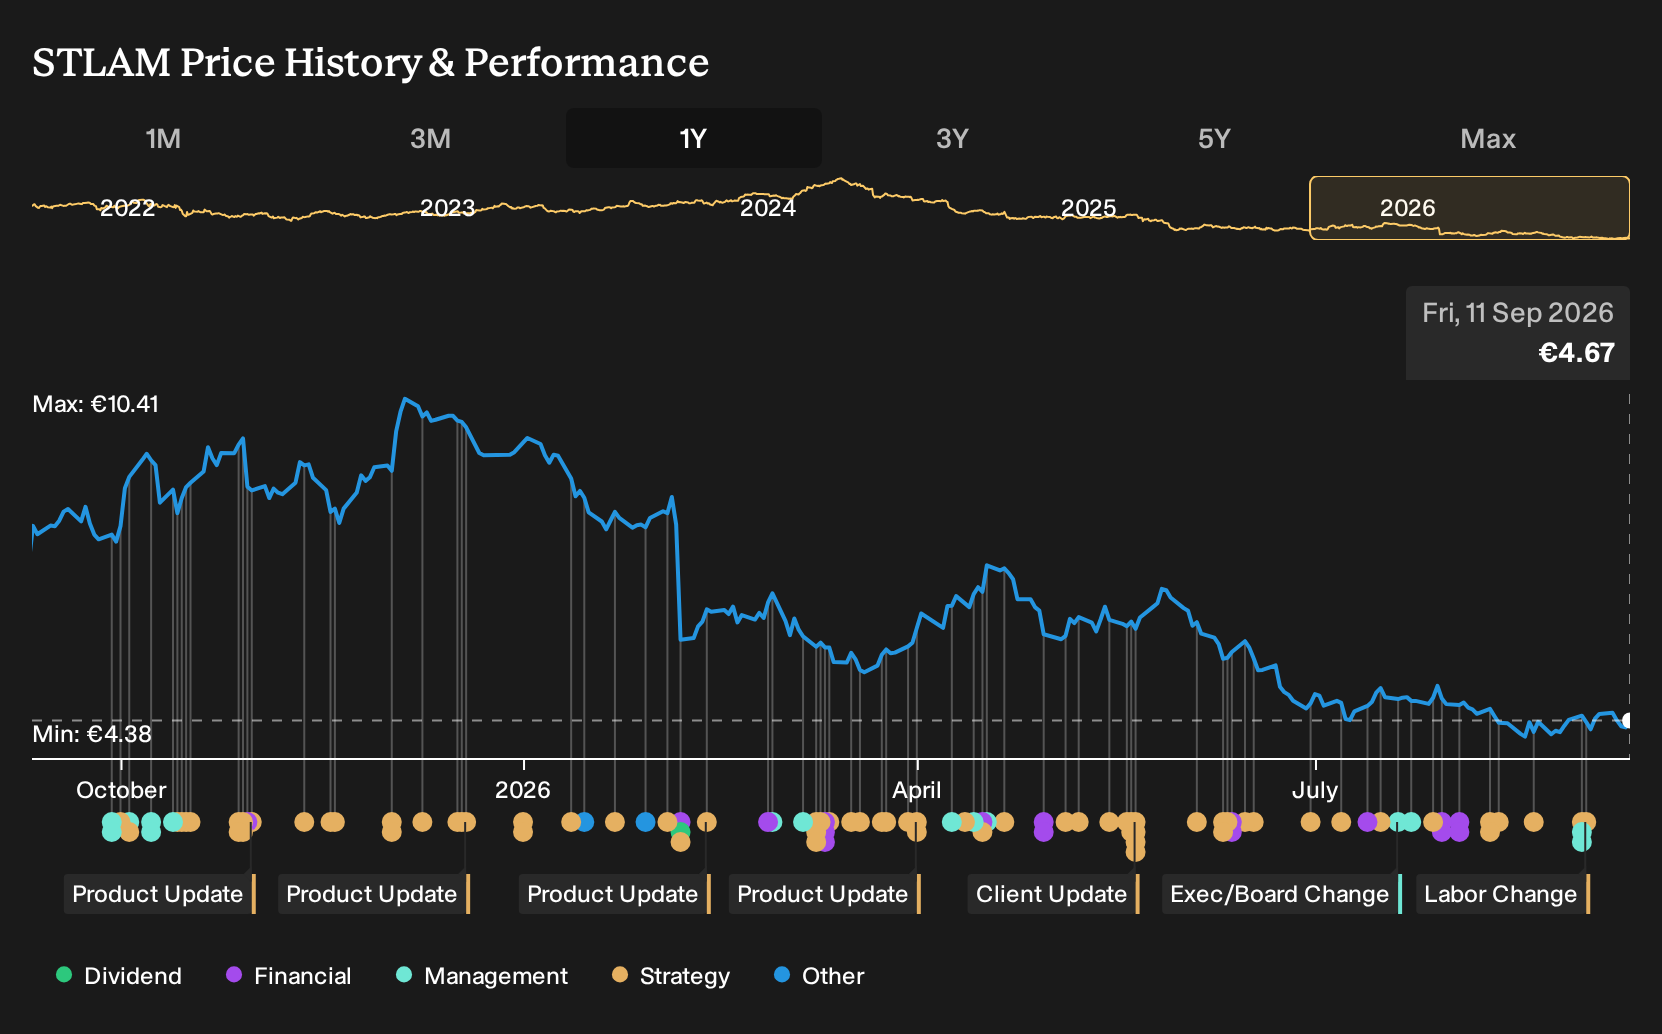
- Stellantis is contending with fresh labor friction in Canada, delayed reopening plans at the Belvidere plant and a possible sale of the idled Brampton facility, while also pushing new investment into its European van operations.
- The combination of union impasse, uncertain North American plant utilization and long lead times on capacity resets concentrates execution risk in Stellantis’ manufacturing footprint.
- We will now examine how Stellantis' investment narrative is shaped by the Unifor impasse over the Brampton plant and broader plant uncertainty.
Scan how Stellantis handles labor friction and plant resets, then widen your watchlist with our curated list of solid balance sheet and fundamentals (194 results) that may weather similar shocks more predictably.
Stellantis Investment Narrative Recap
To own Stellantis, you need to believe the group can turn a sprawling, complex manufacturing base into reliable cash generation as electrification, software and regional mix shift play through. The short term swing factor sits in execution on plant resets and keeping core profit pools such as European vans and North American Jeeps and Rams running efficiently.
The latest Canadian labor standoff and Brampton uncertainty keep the biggest present risk squarely on industrial execution. Repeated capacity moves, long lead times on Belvidere and the potential Brampton sale cluster timing risk around product launches and utilization. That matters far more than sentiment or near term share price moves.
The memorandum to sell the idled Brampton facility to Roshel is the most relevant development for you. It ties directly into Unifor’s core concern, the future of 2,200 laid off workers, and into Stellantis’ broader effort to reshape its North American footprint while it allocates more than €1b to European van capacity.
If the Brampton plant shifts from idle auto facility to a defense focused site, the near term catalyst becomes whether Stellantis can re anchor Canadian operations at Windsor and Etobicoke while keeping union relations workable. Execution here interacts with other catalysts such as new BEV platforms and cost programs, since labor disruption could offset progress elsewhere.
Stellantis' current analyst narrative points to revenues of €174.5b and earnings of €4.9b by 2029, based on assumed yearly top line growth of 2.7% and a move from an earnings loss of €19.5b today to that €4.9b profit, which implies roughly a €24.4b earnings swing over the period.
Uncover why Stellantis' fair value indicates a 24% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on labor risk and more on Stellantis’ push into connected cars and software services. They were already pencilling in €189.6b of revenue and €10.9b of earnings by 2029. Those projections did not factor in the Brampton impasse or new leadership moves, so investors may want to monitor how views evolve and compare several angles before deciding how this story fits within a portfolio.
Explore 10 other Stellantis fair value estimates, including one that suggests as much as 257% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment performance often comes from independent thinking, so trust your own analysis.
- A great starting point for your Stellantis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Stellantis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stellantis' overall financial profile at a glance.
Looking For More Investment Ideas Beyond Stellantis?
Once you have a view on Stellantis, it can help to line it up against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- For investors who want resilient balance sheets and steady fundamentals, scan our 97 resilient stocks with low risk scores that may hold up better when conditions get choppy.
- If the focus is on finding potential bargains, compare Stellantis with a curated 183 high quality undervalued stocks that screens for quality plus pricing that may look appealing.
- Income focused portfolios can tap into a 164 dividend fortresses that aims to combine higher yields with companies that show more durable financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com