


Earnings Beat Might Change The Case For Investing In Corpay Stock (CPAY)
- Corpay reported strong second quarter 2026 results, with adjusted earnings per share rising 36% year over year and revenue growing 21%, both above analyst expectations.
- The earnings beat suggests Corpay is converting its payments footprint into higher profitability, indicating effective cost control and solid demand across its core platforms.
- We will now look at how Corpay's investment narrative could be affected by this strong second quarter earnings and revenue beat.
Review how Corpay's momentum compares to other payment and fintech players by exploring our curated list of 16 high quality undiscovered gems with similar earnings strength.
Corpay Investment Narrative Recap
To own Corpay, you need to believe the business can keep scaling corporate, vehicle, and lodging payments while holding on to attractive economics in a crowded field. The latest 36% jump in adjusted EPS and 21% revenue lift point to healthy demand and operating discipline. The key near term swing factor remains execution in cross border and payables automation, where volume trends now look supportive.
The main near term watchpoint is risk around leverage and cash generation, since debt is not well covered by operating cash flow. Strong quarterly profits ease some concern but do not remove it. Rising compliance costs, cyber security spend, and intense fintech competition still sit close to the front of the risk queue.
With no fresh corporate announcements tied directly to this quarter, the most relevant context is Corpay's ongoing push in areas already flagged as catalysts. Management has been leaning into cross border payments, multicurrency accounts, and accounts payable automation, using acquisitions and product rollouts to widen its reach across geographies and customer types.
The latest earnings beat gives those existing projects more breathing room. Stronger profitability can help absorb integration costs, technology spend, and higher regulatory overheads. This matters for a company using external borrowing as its main funding source. For you, the question is whether this operational momentum offsets execution, competition, and lodging segment risks that remain very much in play.
Corpay's current analyst narrative points to revenues of $6.6 billion and earnings of $1.9 billion by 2029, based on assumed yearly revenue growth of 9.4% and an earnings increase of about $800 million from the $1.1 billion reported today.
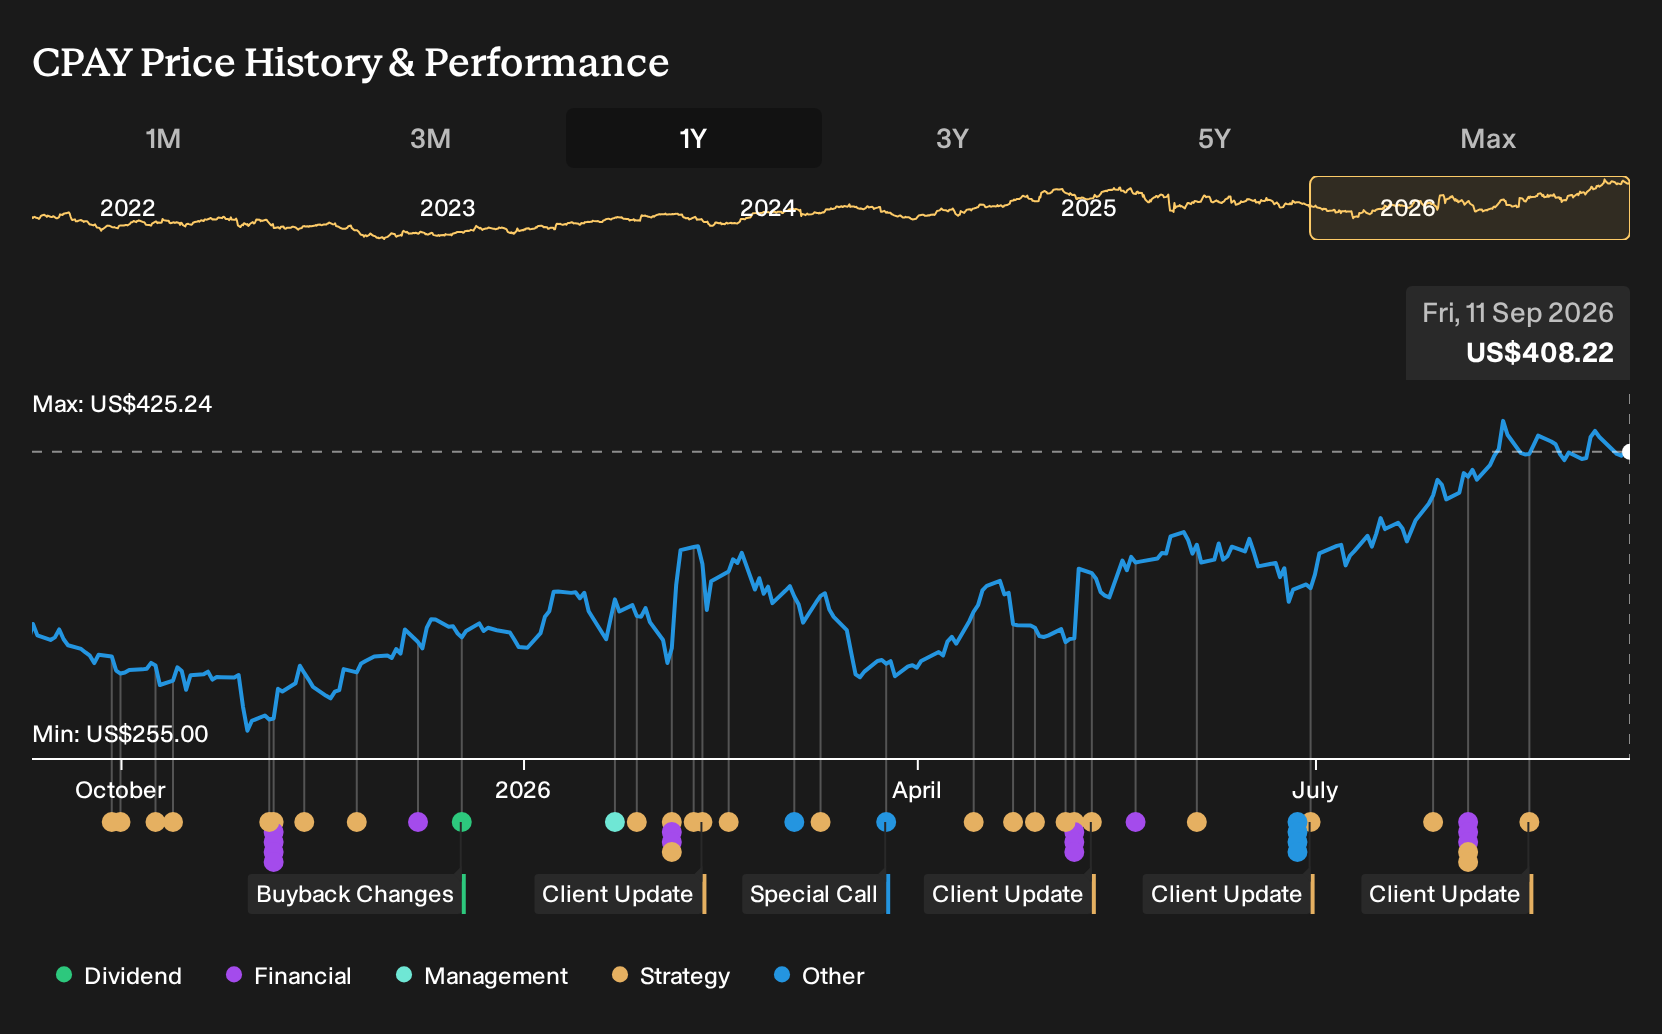
Uncover why Corpay's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span from US$350.44 to more than US$633,888,868,346.64, so expectations on Corpay are extremely spread out. That gap mirrors how differently private investors weigh cross border expansion and payables automation against rising cyber, regulatory, and competitive pressures. Explore these contrasting views before leaning on any single story.
Explore 3 other Corpay fair value estimates, including one that suggests as much as 155281188560% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Corpay research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Corpay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corpay's overall financial health at a glance.
Looking For More Investment Ideas Beyond Corpay?
Once you have a view on Corpay, it helps to widen the lens and compare it with other businesses that share similar financial traits. The Simply Wall St Screener is built for that kind of side by side work, so you can test your thesis against a broader set of opportunities.
- If you want potential value opportunities with strong fundamentals, start by scanning a 31 high quality undervalued stocks that already clear a quality bar on cash flows and balance sheets.
- For income focused investing, filter for steady payers using a curated group of 6 dividend fortresses that combine yield with financial resilience.
- To keep risk in check while you search for ideas beyond Corpay, narrow your universe to a 11 resilient stocks with low risk scores that score well on stability and downside protection.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com