


Emerson Electric (EMR) Stock Looks Fully Priced With Fair Earnings But Weak Value
Emerson Electric stock has delivered a strong 74.2% total return over the past five years. However, its current checks point to a company that no longer screens as a clear bargain at today’s price of US$152.19.
- A roughly 74.2% gain across five years signals that a lot of optimism is already embedded in Emerson Electric shares.
- Future execution on margins and cash flow can support the current valuation. Any stumble in converting orders into steady free cash generation may weigh on what investors are willing to pay.
- The broader valuation framework leans expensive, with Emerson Electric scoring 2 out of 6 on the value checks. This suggests it does not screen as a clear value opportunity right now.
The issue now is whether Emerson Electric’s current share price already reflects most of the reasonably optimistic scenarios that investors might expect over the next few years.
Broaden your watchlist beyond Emerson Electric by scanning our hand picked 31 high quality undervalued stocks that currently combine stronger value checks with solid business quality.
Is Emerson Electric Fairly Priced on Earnings?
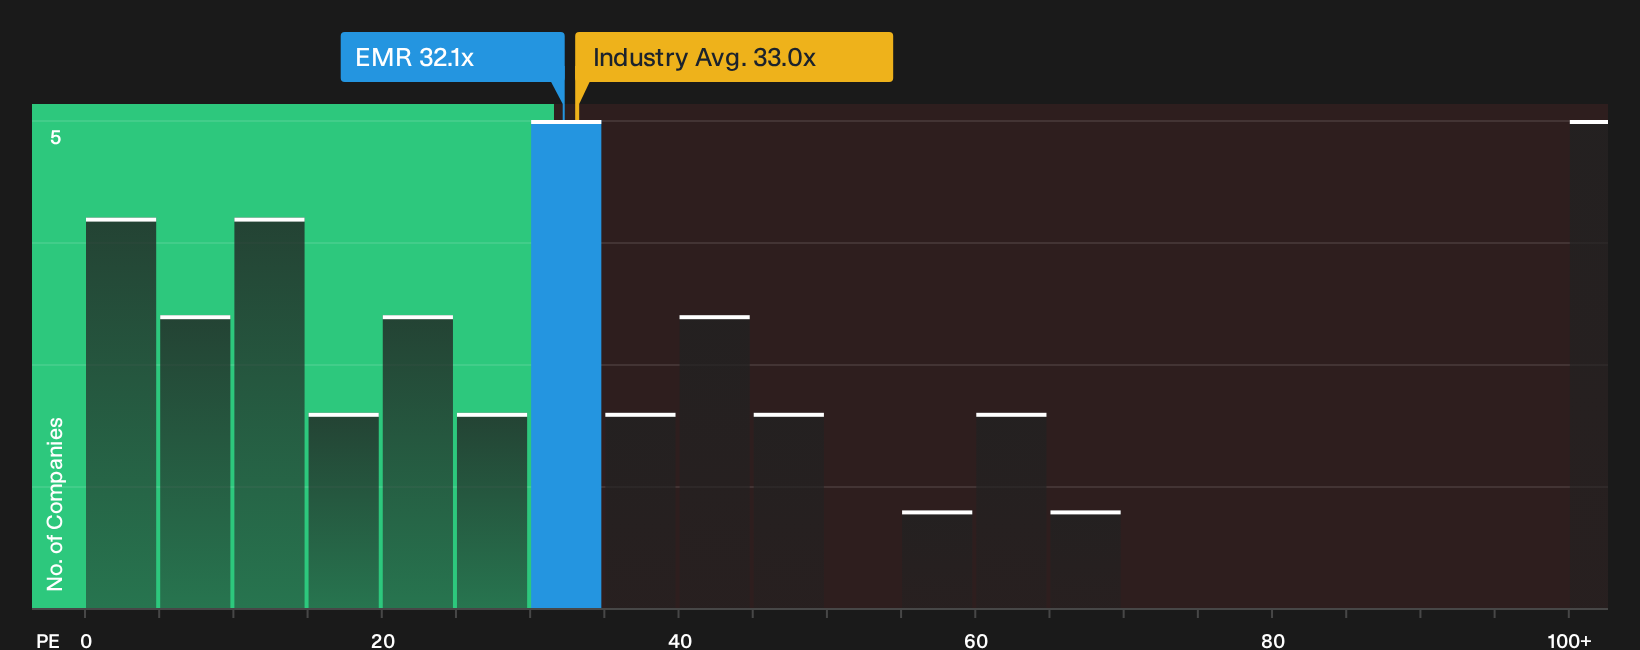
The P/E ratio is a useful starting point for Emerson Electric because earnings remain a key anchor for how investors look at this industrial group. At today’s price, the stock trades on about 33.0x earnings, slightly below the electrical equipment industry average of around 34.1x and below the broader peer group on roughly 43.8x. That places Emerson Electric somewhere in the middle of the pack, neither screamingly cheap nor clearly stretched on this single yardstick.
A more tailored view comes from the fair P/E ratio estimate of about 30.4x, which reflects factors such as Emerson Electric’s risk profile, profitability and sector. The current multiple sits only modestly above that level, so there is not a large gap for investors to lean on, either as a clear discount or a punchy premium.
On the P/E multiple, Emerson Electric shares look roughly fairly valued, with pricing close to what the earnings profile and sector backdrop would justify.
See what the numbers say about this price — find out in our valuation breakdown.
The Emerson Electric Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Emerson Electric valuation puzzle leaves off. They spell out which assumptions on growth, margins and earnings would need to hold for Emerson Electric's shares to be worth materially more or less than today’s price. Each one treats fair value as a thesis about the business that can be revisited over time rather than a one off snapshot.
Views on Emerson Electric could hardly be further apart, with one camp leaning into the automation upside and the other focused on trade and digital risks.
Bull case: 11% undervalued
"The accelerating adoption of digital automation and artificial intelligence solutions in global industrial markets is fueling strong demand for Emerson's advanced software platforms and AI-enabled products, such as Ovation 4.0 and Nigel AI adviser, which is resulting in robust order growth and positions the company for sustained revenue expansion…"
Read the full Bull Case to see why Emerson Electric could be undervalued
Bear case: 18% overvalued
"The accelerating trend toward global supply chain localization and rising protectionism exposes Emerson to higher input costs and increased volatility in overseas demand, particularly as tariff headwinds are offset by aggressive pricing and operational measures that may not be sustainable in the long term…"
Read the full Bear Case to see why Emerson Electric could be overvalued
Do you think there's more to the story for Emerson Electric? Head over to our Community to see what others are saying!
The Bottom Line
Emerson Electric now trades on earnings that look roughly in line with its sector, so the easy valuation argument has faded. The broader value checks are weak, which points to limited room for error if expectations on margins or cash generation slip. For investors already following Emerson Electric, the key question is whether the company can turn its automation and software opportunities into durable, high quality free cash flow that fully supports the current multiple. That execution gap is where the bull and bear views really part ways.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com