


How CEO Succession At Sprouts Farmers Market Stock Has Changed Its Investment Story
- Sprouts Farmers Market has completed a long planned leadership transition, with President and COO Nick Konat set to become CEO and join the Board at the start of the 2027 fiscal year, while current CEO Jack Sinclair moves to Executive Chairman.
- The appointment places an operator with deep merchandising and supply chain experience at the center of Sprouts Farmers Market’s decision making. This could influence how the retailer balances growth spending, store expansion, and profitability discipline in a competitive health focused grocery space.
- We will look at how Sprouts Farmers Market’s investment narrative shifts as Nick Konat’s upcoming CEO move reshapes execution priorities.
Sprouts Farmers Market Investment Narrative Recap
To stay invested in Sprouts Farmers Market, you need to believe the healthy grocery format can keep pulling in shoppers even as traditional retailers sharpen their organic and fresh assortments. The most important short term catalyst is execution on new store productivity and supply chain projects, given ongoing consumer interest in wellness focused food.
The biggest risk remains margin pressure from competition, labor costs, and the complexity of in sourcing and distribution center expansion. The new headquarters and upcoming CEO transition look more like continuity moves than sharp shifts, so they do not materially change that near term risk reward balance.
The new 180,000 square foot Phoenix headquarters is the clearest recent announcement that touches those execution themes. It places Sprouts Farmers Market’s support office, a flagship store, and complementary retail on a single 7 acre campus, which can make coordination across merchandising, supply chain, and store development more practical.
For a reader focused on catalysts, this campus mainly matters if it helps Sprouts manage new market expansion, private label growth, and self distribution projects with fewer bottlenecks. It can also add some fixed cost, so the key operational question is whether efficiencies in planning, vendor management, and project delivery offset that over time.
Sprouts Farmers Market Analyst Assumptions In Plain English
Sprouts Farmers Market now has a fairly tight set of expectations from Wall Street that tie its growth projects to specific revenue and profit numbers. Analysts are building their models around yearly revenue growth of 9.2% and a modest squeeze in profit margins from 5.6% today to 5.2% in roughly three years, which frames the trade off between expansion and cost control.
On the earnings line, forecasts point to Sprouts Farmers Market generating current earnings of US$502.9 million and reaching US$606.1 million by around 2029. That implies an earnings increase of about US$103 million on these estimates, with consensus also calling for earnings per share of US$6.97 as share count declines by an expected 4.58% a year over the next three years.
Valuation work in the same reports ties these operating assumptions to a revenue target of US$11.7b and earnings of US$606.1 million in 2029. To line up with the analyst case, Sprouts Farmers Market would be trading on a P/E of 15.9x those 2029 profits, compared with 15.8x today and a current US Consumer Retailing industry multiple of 19.7x.
Sprouts Farmers Market's narrative projects US$11.7b revenue and US$606.1 million earnings by 2029. This setup uses 9.2% yearly revenue growth and an earnings increase of about US$103 million from current earnings of US$502.9 million.
Uncover how Sprouts Farmers Market's fair value indicates a 33% potential upside to its current price before the discount closes.
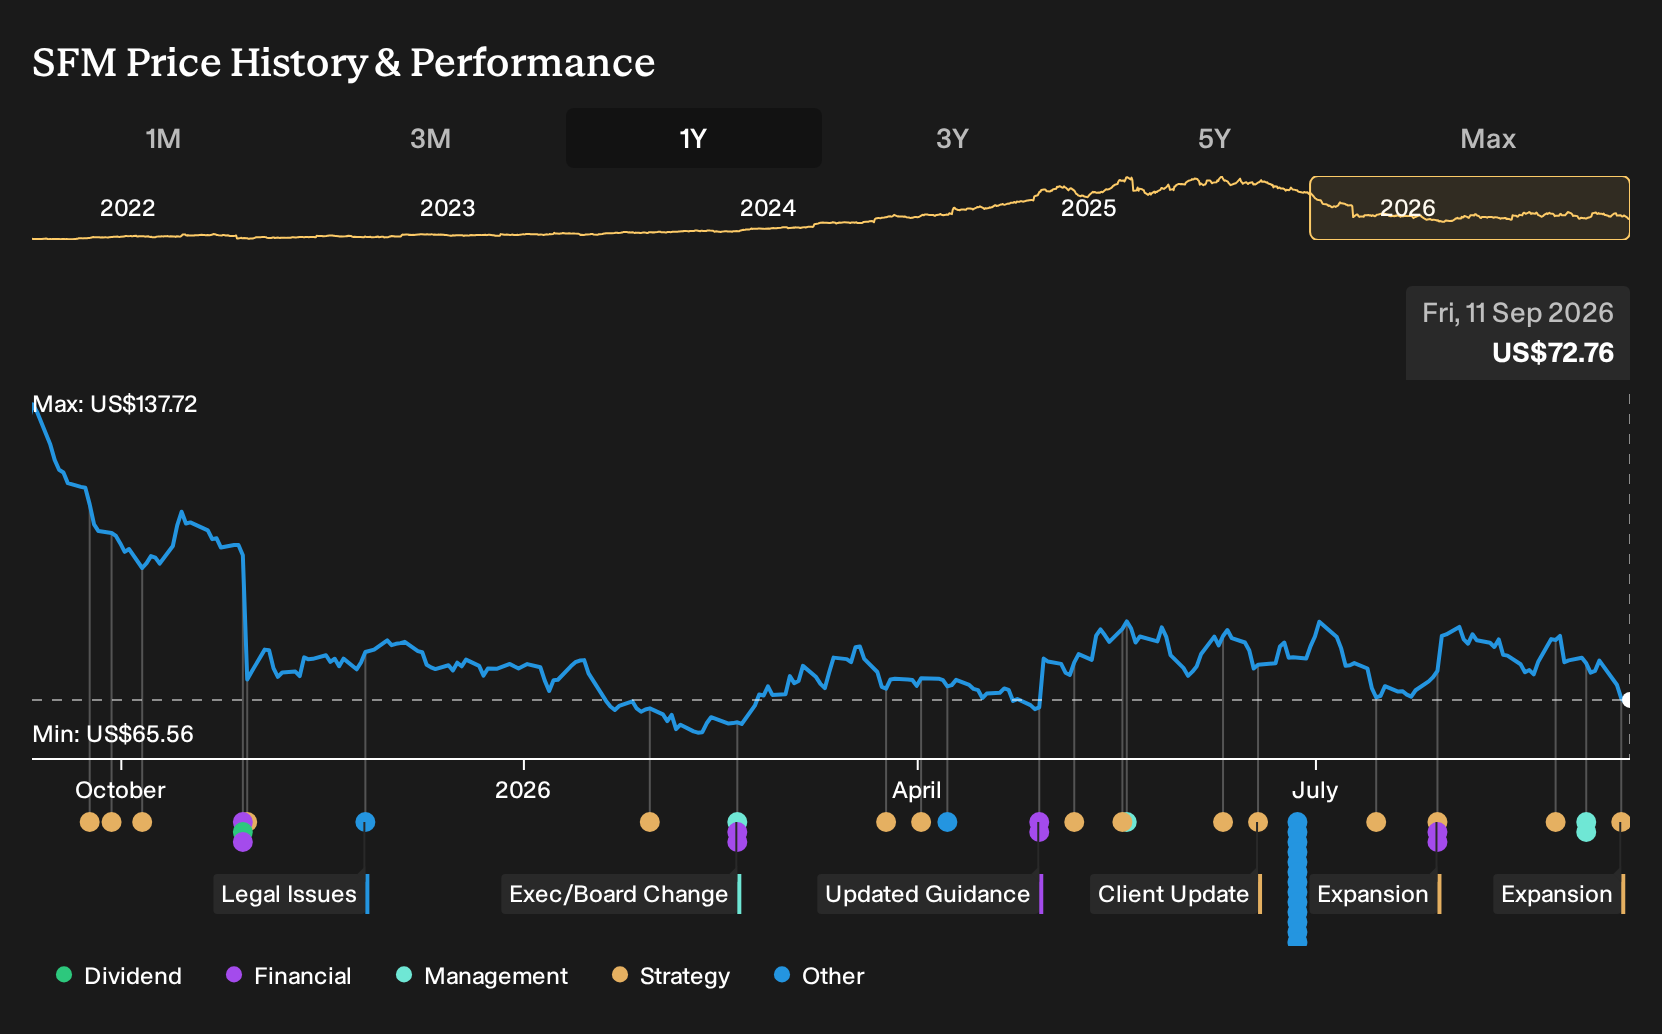
Exploring Other Perspectives
For Sprouts Farmers Market, the alternate view puts execution risk on the new store pipeline front and center. The most cautious analysts were modeling revenue of about US$11.2b and earnings near US$554.5 million by 2029 before this headquarters and CEO news. That is a meaningfully lower bar than consensus. Consider it a prompt to compare several narratives and determine which assumptions you find more realistic as the story evolves.
Explore 7 other Sprouts Farmers Market fair value estimates, including one that suggests it could be worth just $92.59.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Sprouts Farmers Market research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Sprouts Farmers Market. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sprouts Farmers Market's overall financial health at a glance.
Looking For More Sprouts Farmers Market Style Ideas?
If the Sprouts Farmers Market story has you thinking about portfolio gaps, use the Simply Wall St screener to widen your opportunity set with companies that share the kind of balance sheet strength and fundamentals you might be looking for.
- For investors who care most about resilient finances and room to reinvest, start with a list of solid balance sheet and fundamentals (23 results) that can help you stress test ideas beyond Sprouts.
- If you want potential mispricing opportunities backed by strong fundamentals, scan through a 16 high quality undiscovered gems and see which businesses merit deeper research.
- For a focus on steadier profiles where risk scores are lower, sort through a 11 resilient stocks with low risk scores and compare how those companies stack up against your current holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com