


3 Oil Transport Stocks Retail Investors Are Watching After Oil Hit $100
Oil prices above US$100, diesel near US$6 a gallon and talk of Venezuelan output returning in size have pushed midstream pipes and tanker routes back into the spotlight. Cash is flowing through the system, not just at the wellhead. Miss how that reshapes fee income and freight demand and you risk sitting out a powerful move. This article walks through three stocks from the screener that appear closely aligned with this news shock and explains where their exposure could matter most for your portfolio decisions.
The three stocks below are a starting sample, while the full Oil & Gas Midstream and Tanker Transport screen surfaced 18 more companies with equally interesting fee and freight stories that are not covered here. To identify and analyze the highest conviction plays across this space, head straight to the Oil & Gas Midstream and Tanker Transport screener.
Kistos Holdings (AIM:KIST)
Overview: Kistos Holdings develops and produces natural gas and other hydrocarbons across the UK, Norway and the Netherlands, with some midstream processing and storage links.
Operations: Kistos generated about US$213 million from oil and gas exploration and production, with US$106 million from Norway, US$79 million from the UK and US$27 million from the Netherlands.
Market Cap: £266 million
Kistos Holdings ties into the midstream and transport theme through sizeable European gas output that requires pipeline, processing and shipping capacity to reach market. The business already runs oil processing, offloading and gas storage, and is built on a production base that could become more significant if a single pressure point in its funding and profitability story is resolved cleanly.
If that funding pressure point is what matters most for you, go straight to the Kistos Holdings financial health report to see how Kistos Holdings’ balance sheet could reshape the story.
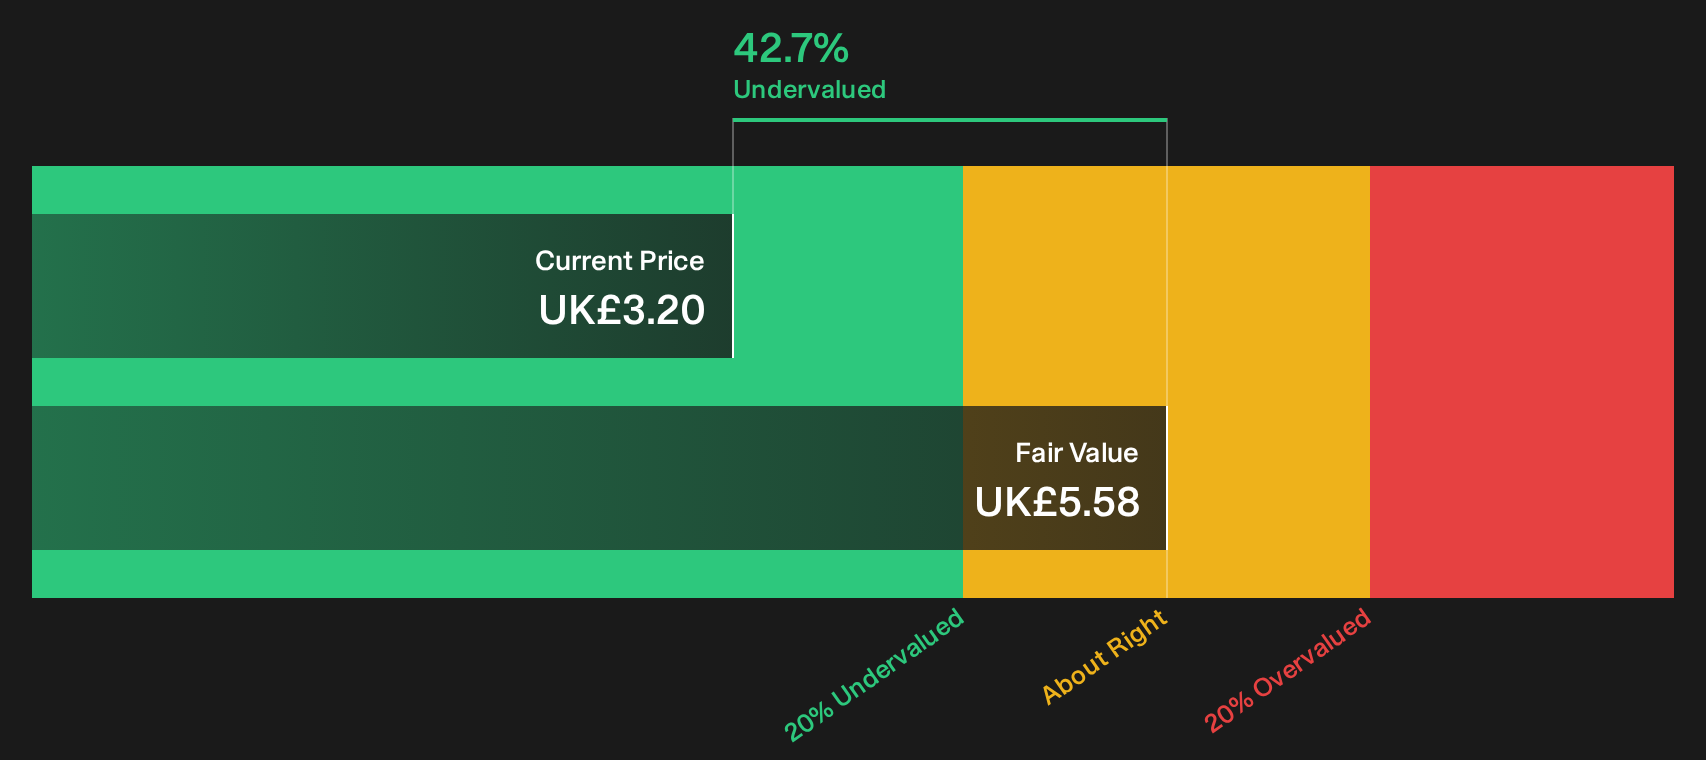
James Fisher and Sons (LSE:FSJ)
Overview: James Fisher and Sons provides specialist marine services across energy, defence and maritime transport, supporting offshore projects, subsea work and tanker logistics worldwide.
Market Cap: £216 million
For the Oil & Gas Midstream and Tanker Transport theme, James Fisher and Sons matters because its ships, subsea crews and port services sit right where crude and products physically move.
"Although the Defense division now has a £315 million order book and a special security agreement in the U.S., contract phasing, intense competition for rising defense budgets and the need to scale local presence could slow how fast these orders convert into revenue and operating profit."
What happens to James Fisher and Sons’ margins if one quietly growing part of its energy transport work absorbs more capital than expected?
That capital question is exactly what the full narrative for James Fisher and Sons unpacks, including where James Fisher and Sons could be quietly accelerating or stalling beneath the headline order book.
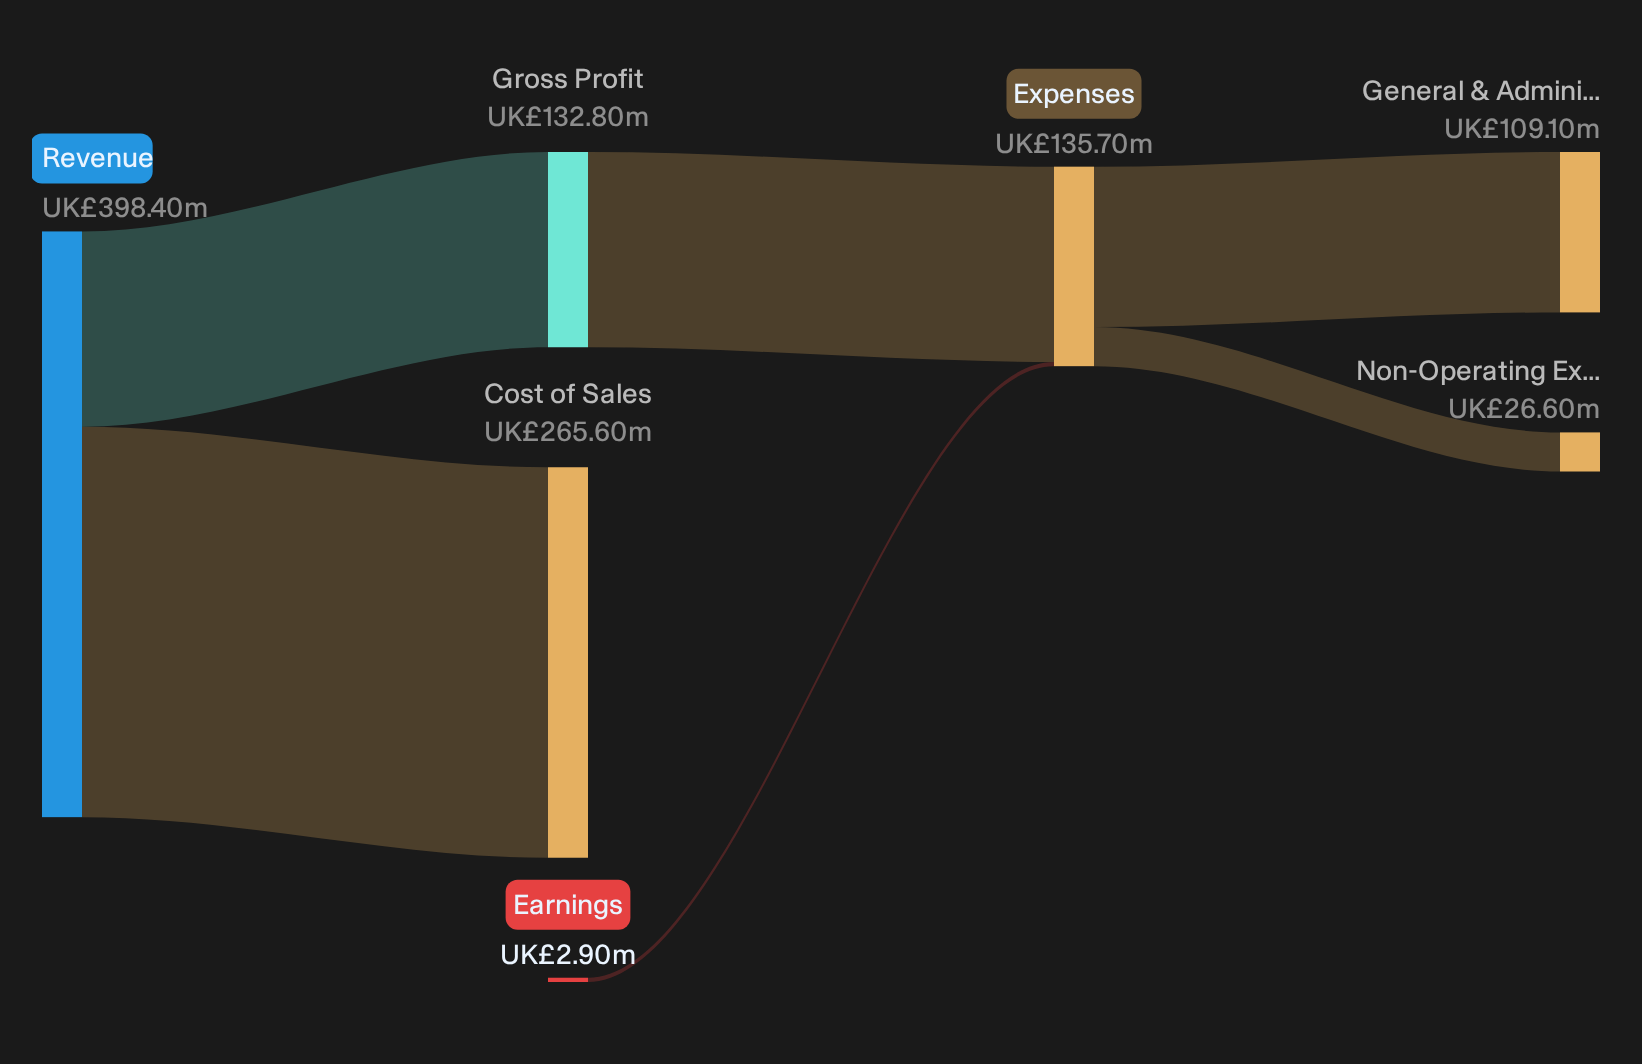
Stabilis Solutions (SLNG)
Overview: Stabilis Solutions provides LNG-based clean energy production, storage, transport and fueling services across North American industrial, marine and power markets.
Operations: Stabilis Solutions generates about US$55.9 million from oil and gas refining and marketing, with roughly US$52.3 million from the United States and US$3.6 million from Mexico.
Market Cap: US$98.8 million
Stabilis Solutions plugs into this midstream and transport theme as a smaller LNG logistics player. It offers fee-like exposure to fuel supply chains that sit slightly apart from crude and diesel headlines.
"The anticipated signing of multiple long-term, multi-year LNG offtake agreements across marine, aerospace, and power generation sectors is likely to underpin revenue growth and provide greater earnings visibility as these contracts support capacity expansion and project financing."
What happens to Stabilis Solutions’ future margins and growth pace hinges on how one tight funding and utilization pressure ultimately resolves.
That funding squeeze and utilization risk are exactly what the full narrative for Stabilis Solutions unpacks, including how Stabilis Solutions could turn new LNG contracts into faster cash flow growth.

Seeking Alternatives Beyond Oil Pipes?
Fresh themes move fast. Breakout stories, quiet momentum and falling valuations rarely stay under the radar for long. Scan curated ideas before the crowd and act now.
- Spot cash-generating outliers early and review the 9 high quality undervalued stocks before stronger momentum gets fully priced in and the easy mispricing edge starts dropping away.
- Pursue steady portfolio ballast and assess the 1 dividend fortresses while yields remain elevated and income investors have not fully crowded into the same payouts.
- Track the next infrastructure backbone and scan the 89 AI infrastructure stocks while these enablers stay under the radar for now and valuations still look grounded.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com