


3 U.S. Bank Stocks With Earnings Riding High Interest Margins
Markets are being pulled in opposite directions by stubborn 3.4% inflation, surging energy costs and a bond sell off that has the 10 year Treasury near 5% and the 30 year at multi decade highs. Policy feels tighter, valuations feel heavier and rate expectations are shifting under a new Fed Chair. That mix can punish some stocks while rewarding others. This article examines three U.S. financials that are closely tied to those rate moves.
The three stocks below are just a sample, and the full screen surfaced 51 more U.S. banks and insurers with equally compelling stories that are not covered here. To identify and analyze the highest conviction rate beneficiaries directly, head straight into the U.S. Bank and Insurance Financials Benefiting from Higher Interest Rates screener.
Esquire Financial Holdings (ESQ)
Overview: Esquire Financial Holdings is a U.S. commercial bank focused on legal and small business clients, where lending and securities income closely track interest rates.
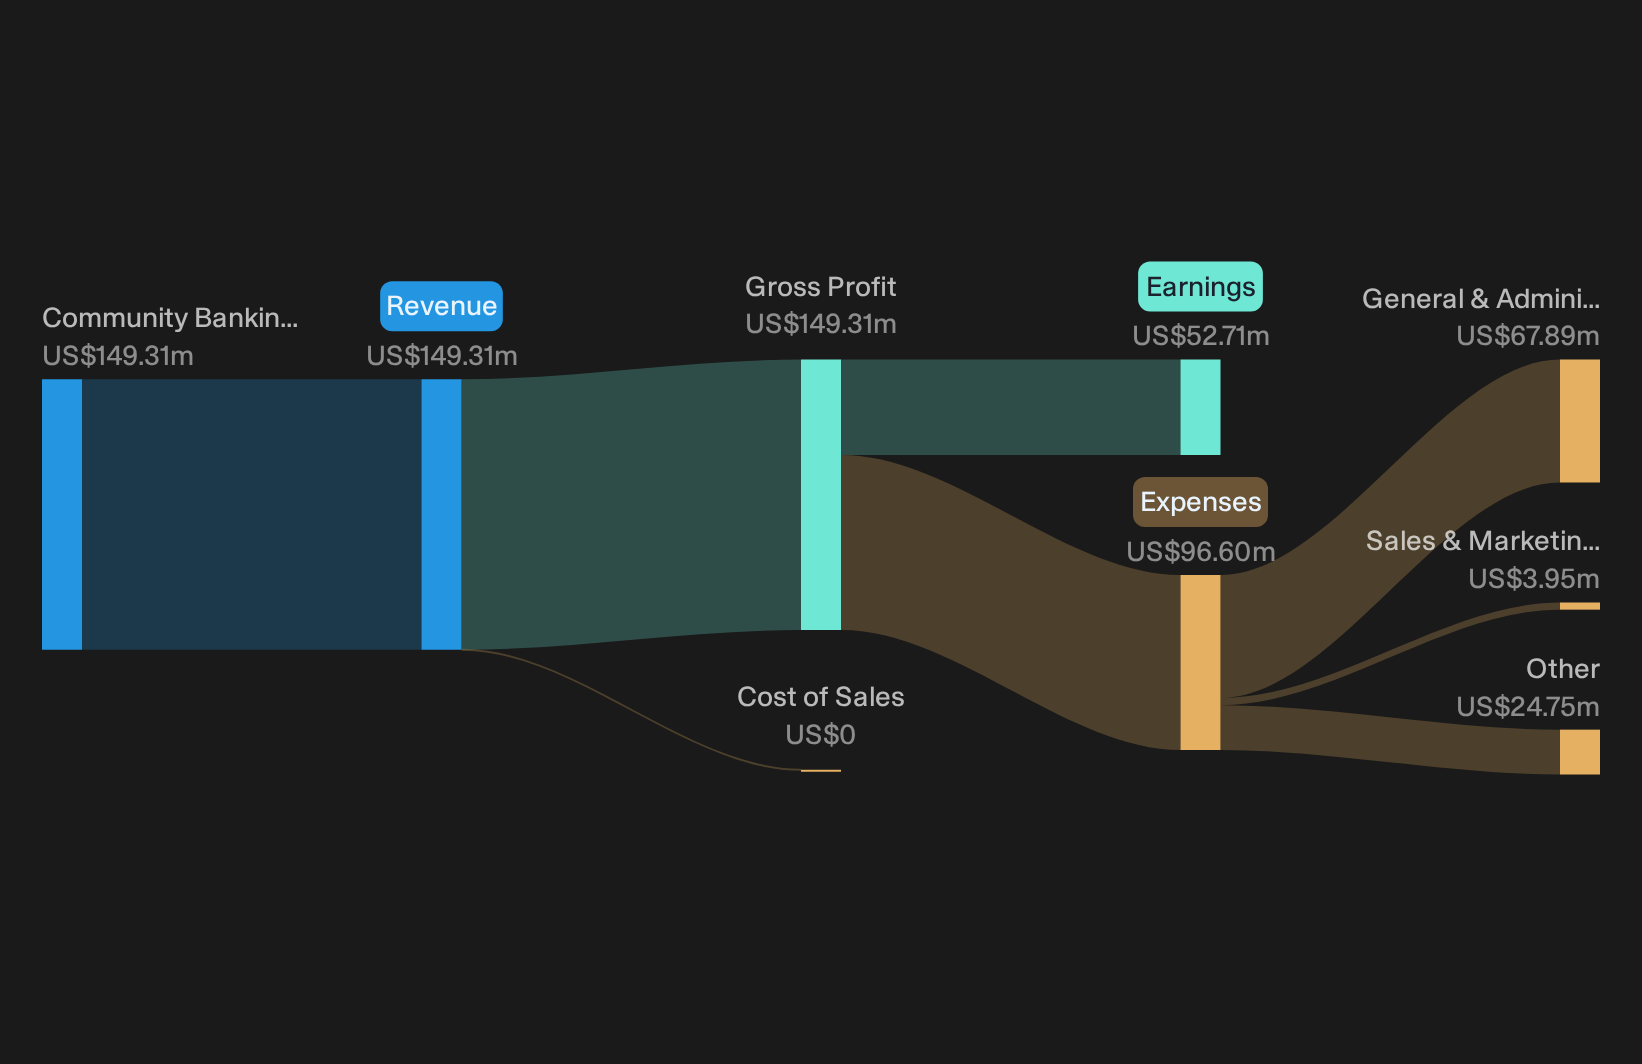
Operations: Esquire Financial generates about US$149 million from community banking activities in the United States, with earnings tied to rate sensitive lending and deposits.
Market Cap: US$1.4b
Esquire Financial Holdings gives you targeted exposure to higher policy rates through a niche legal banking franchise that leans heavily on interest income and reinvestment returns. This is exactly what this screener is built to surface.
"The growth of contingent fee law practices and complex litigation is supporting wider use of specialized financing, which Esquire is already serving through a US$1.22b litigation loan book at about a 9% yield."
What really matters next is how one quiet pressure on funding costs and lending appetite shapes the durability of those rich margins.
That funding squeeze question is exactly what the full narrative for Esquire Financial Holdings tackles, including how Esquire Financial Holdings might react if deposit costs start accelerating faster than lending yields.
First Bancorp (FBNC)
Overview: First Bancorp is a regional U.S. bank that collects local deposits and lends them out across households and businesses, so earnings closely track interest margins.
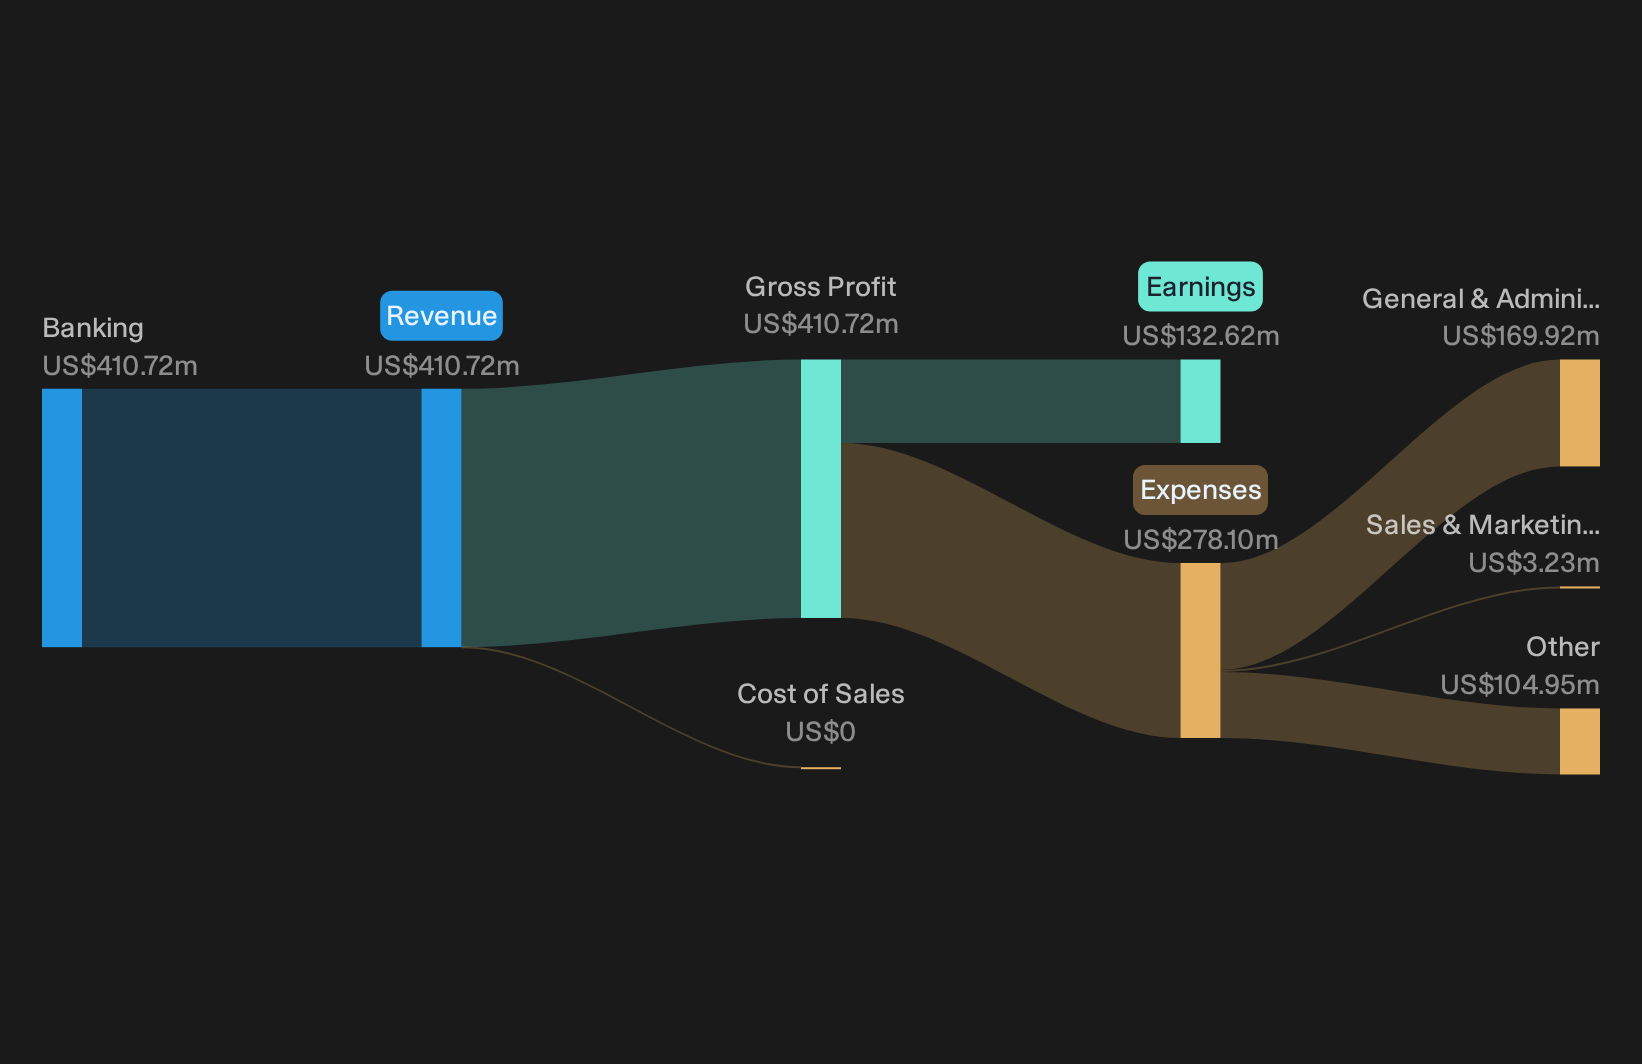
Operations: First Bancorp generates about US$411 million from banking activities in the United States, tying its revenue to rate sensitive lending and deposits.
Market Cap: US$2.7b
First Bancorp fits directly into the screener’s rate theme, with net interest income driving earnings and Q2 2026 results reflecting spreads on a broad loan and deposit base. Investors following this regional lender are effectively monitoring how funding costs may influence the net interest margin if pressures on funding emerge.
If you want to see how those funding pressures could reshape First Bancorp’s earnings profile, go straight to the analyst forecasts for First Bancorp for the full rate story.
HBT Financial (HBT)
Overview: HBT Financial is a heartland banking group that collects deposits and makes loans for consumers, businesses, and municipalities in Illinois and Eastern Iowa.
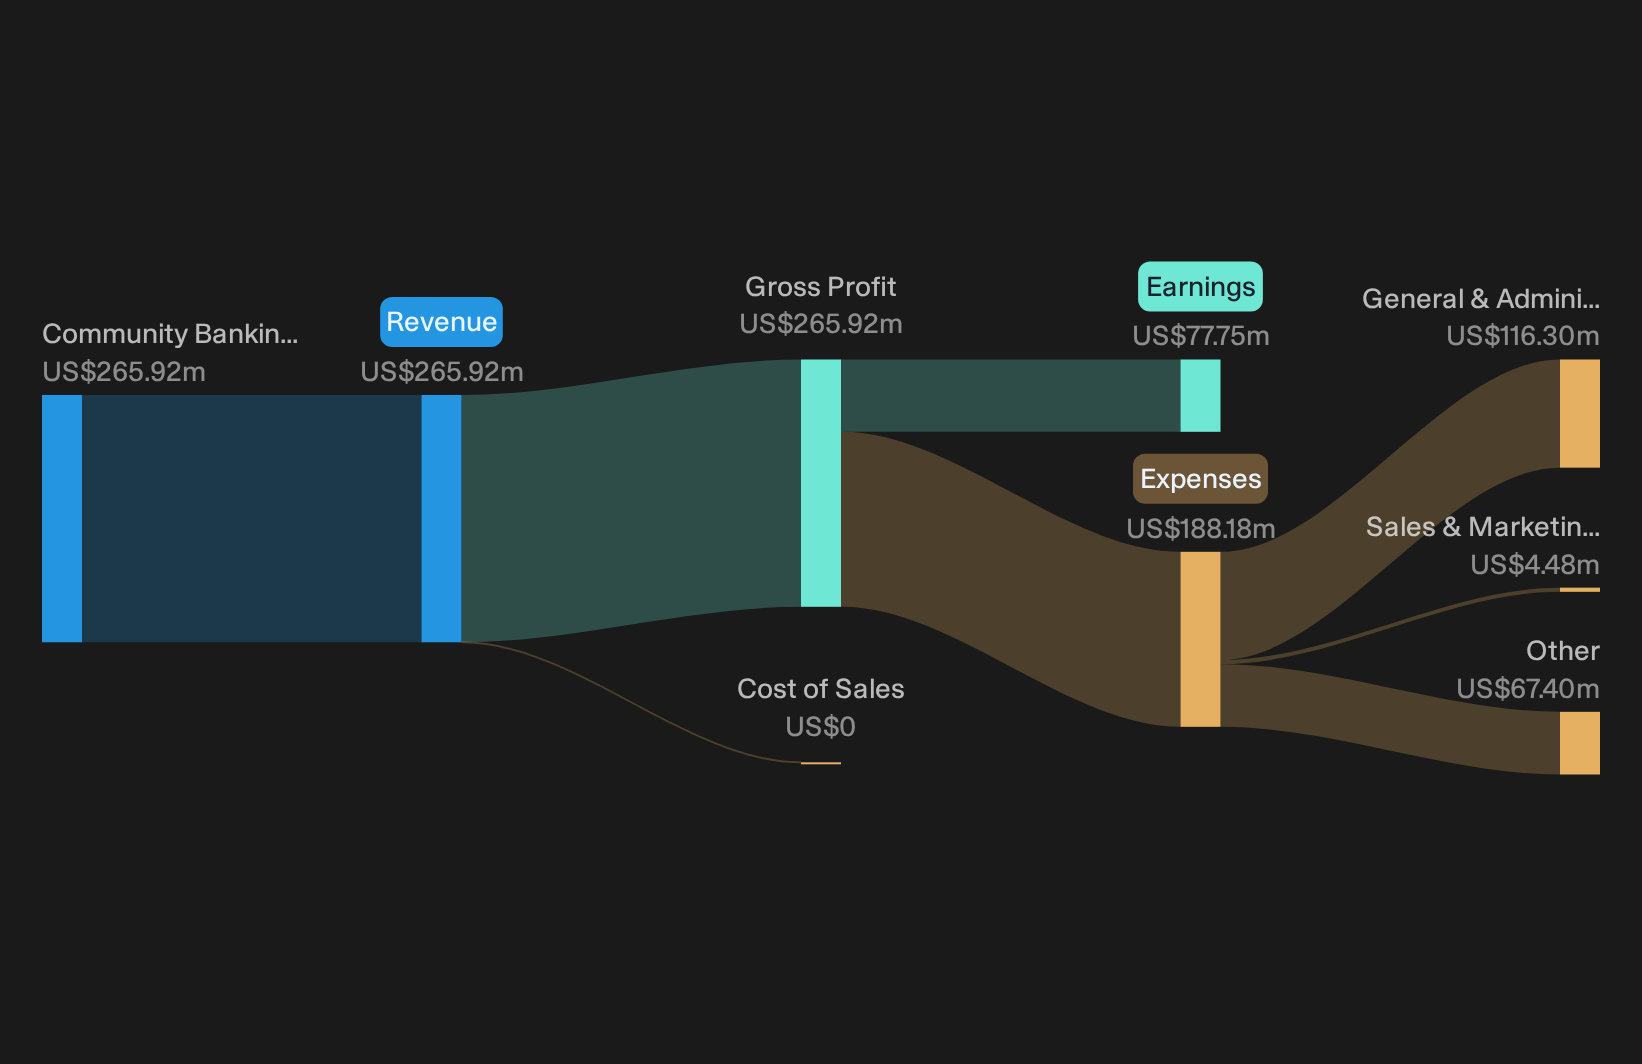
Operations: HBT Financial generates about US$266 million from community banking in the United States, tying its revenue directly to traditional interest spread income.
Market Cap: US$1.3b
HBT Financial sits squarely in the screener theme, with a classic spread-based banking model, net income of US$39.04 million for the first half of 2026 and net profit margins around 29.2% that are sensitive to higher policy rates. Forecast double digit earnings and revenue growth meet the higher rate brief, although the payoff hinges on how one quiet funding pressure develops.
That quiet pressure is already shaping the real story, so head to the 3 key rewards and 1 important warning sign to see where HBT Financial’s spread engine could accelerate or stall.
Curious About Alternatives Worth Exploring?
Fresh opportunities move fast. Breakout themes gain momentum, quiet winners fly under the radar for now, and laggards keep dropping before the crowd catches on, so consider acting promptly.
- Target reliable income ideas by scanning a curated mix of high yield payers through the 6 dividend fortresses while the market focus is elsewhere.
- Hunt for resilient compounders by filtering for businesses with strong finances using the list of solid balance sheet and fundamentals (23 results) before they move out of value territory.
- Ride structural growth trends by reviewing carefully selected enablers of AI demand inside the 89 AI infrastructure stocks while expectations are still catching up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com