


F5 (FFIV) Expands AI Security Tools, Is The Valuation Upside Already Priced In?
F5 (FFIV) has moved deeper into enterprise AI security in September 2026, announcing Workforce AI Security, new AI powered WAF features, and a MuleSoft integration that extends its guardrail tools into agentic workflows.
The recent AI security announcements arrive after a strong run in F5’s shares, with the price at US$411.71 and a year-to-date share price return of 60.43% that points to building momentum despite a modest 1-month dip of 1.03%.
Spot momentum in AI security with F5, then widen your net by scanning hand-picked peers through our 89 AI infrastructure stocks.After a 60% year to date climb and a price sitting just below the average analyst target, F5 now asks a simple question of new money: Does the current valuation still leave enough upside for the risk involved?
Most Popular Narrative: 5.6% Undervalued
F5’s most followed narrative pegs fair value at $436.10, only modestly above the last close at $411.71, which puts the recent AI momentum under a valuation microscope.
Analysts are assuming F5's revenue will grow by 8.1% annually over the next 3 years. Analysts assume that profit margins will increase from 22.0% today to 24.4% in 3 years time.
Want to see what kind of earnings engine those revenue and margin targets build for F5? The narrative leans on a richer profit pool and a firmly higher earnings base. Curious what future valuation multiple this playbook needs to hold together? The full story spells out the numbers sitting behind that fair value tag.
Result: Fair Value of $436.10 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, if F5’s customers lean longer toward hardware or if hyperscalers keep more security in house, that upbeat earnings playbook could look optimistic fast.
Find out about the key risks to this F5 narrative.
Another Look At F5’s Valuation
The popular fair value narrative paints F5 as 5.6% undervalued, yet the current P/E of 32.1x tells a tighter story. That valuation is above the US Communications industry at 31.7x and above F5’s own fair ratio of 27.8x, which points to less margin for error if growth expectations soften.
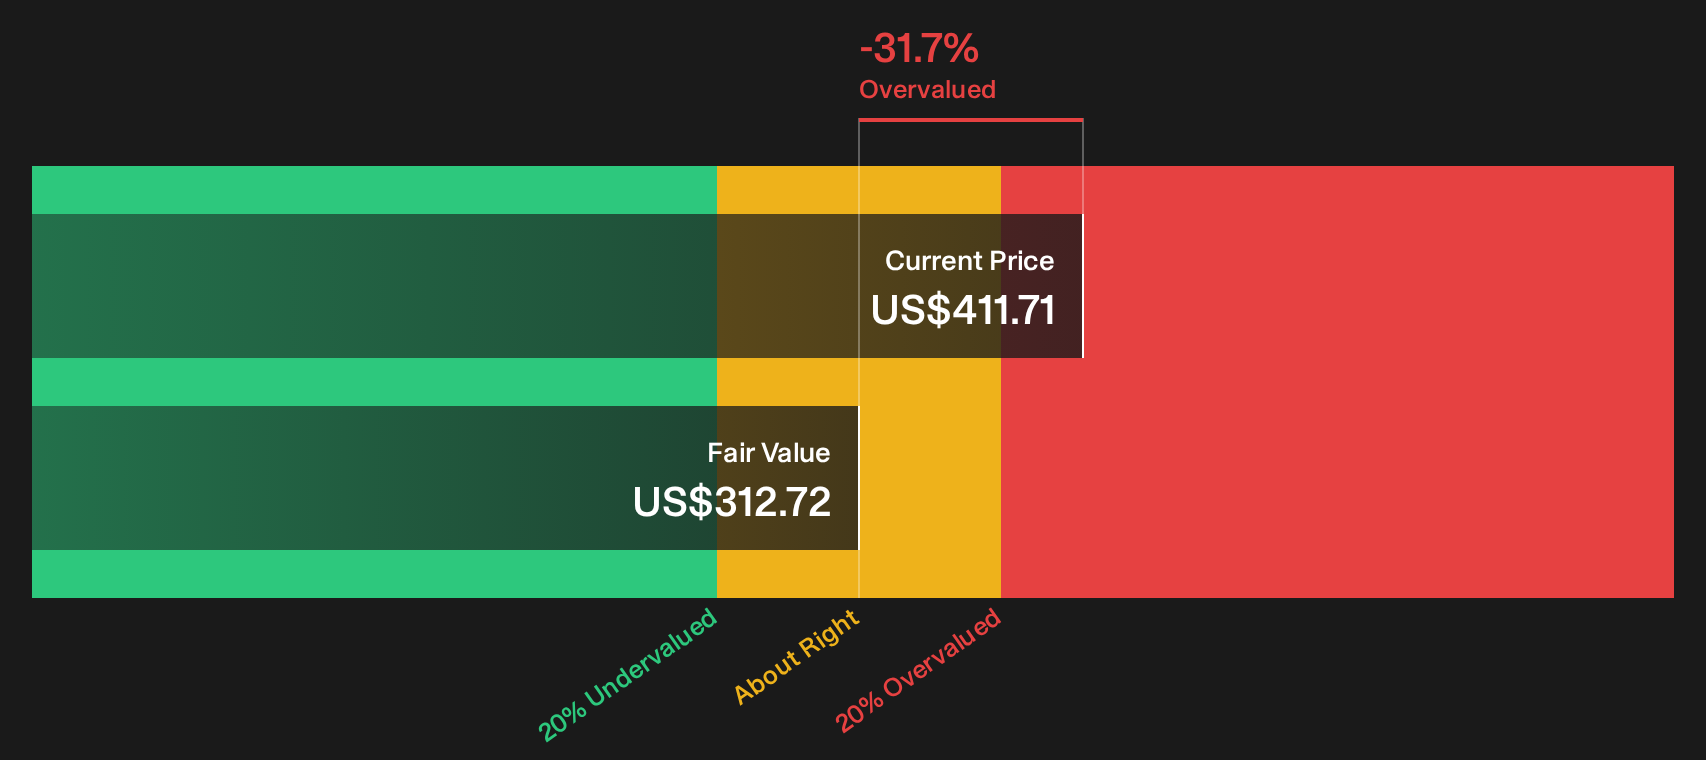
Our DCF model also prices F5 more cautiously, with future cash flow value at $312.72 versus the $411.71 share price, which frames the stock as overvalued on that lens. When one model flags undervaluation and another signals a premium, which yardstick do you trust more for your own process?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Reading through the mixed signals on F5, does the balance of optimism and concern line up with how you see the risk reward today? Take a few minutes to test the numbers, weigh the upside and the weak spots, and then ground your own view in the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond F5?
If F5 sharpened your focus on risk and reward, do not stop here. Broaden your watchlist with data driven ideas that keep you one step ahead.
- Hunt for mispriced quality and see which companies screen as potential value opportunities through our 31 high quality undervalued stocks.
- Strengthen your income stream by reviewing the 6 dividend fortresses that meet a 5%+ yield hurdle while aiming for resilient payouts.
- Dial down portfolio stress and focus on resilience by scanning the 11 resilient stocks with low risk scores that flag lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com