


MannKind (MNKD) Stock May Be 15% Undervalued After Inhaled GLP 1 Deal
MannKind stock has fallen about 33% year to date, yet several valuation checks, including an intrinsic value estimate using a Discounted Cash Flow (DCF) approach, point to a price that sits below what those models suggest. That gap, combined with mixed signals from broader valuation screens, puts the current share level under closer scrutiny for investors trying to assess what is already priced in.
- The share price has declined roughly 33% year to date, which means sentiment has cooled sharply even as some valuation tools indicate potential underpricing.
- The new collaboration with Rose Pharma on an inhaled GLP-1 for weight management can support expectations for future cash flows, while clinical and regulatory execution risk may limit how much value investors are willing to assign today.
- The broader checks point to a mixed picture rather than a clear bargain or clear overvaluation, with MannKind scoring 4 out of 6 on value tests.
For investors, the debate is whether the recent share price weakness already reflects the key risks around MannKind, or whether the intrinsic value estimate is too optimistic about the cash generation that dealmaking and the pipeline can support over time.
Compare MannKind's recent pullback and DCF signals with a curated set of value ideas by scanning 31 high quality undervalued stocks that share a similar mix of discounted prices and fundamental support.
Does MannKind Look Undervalued on Cash Flow?
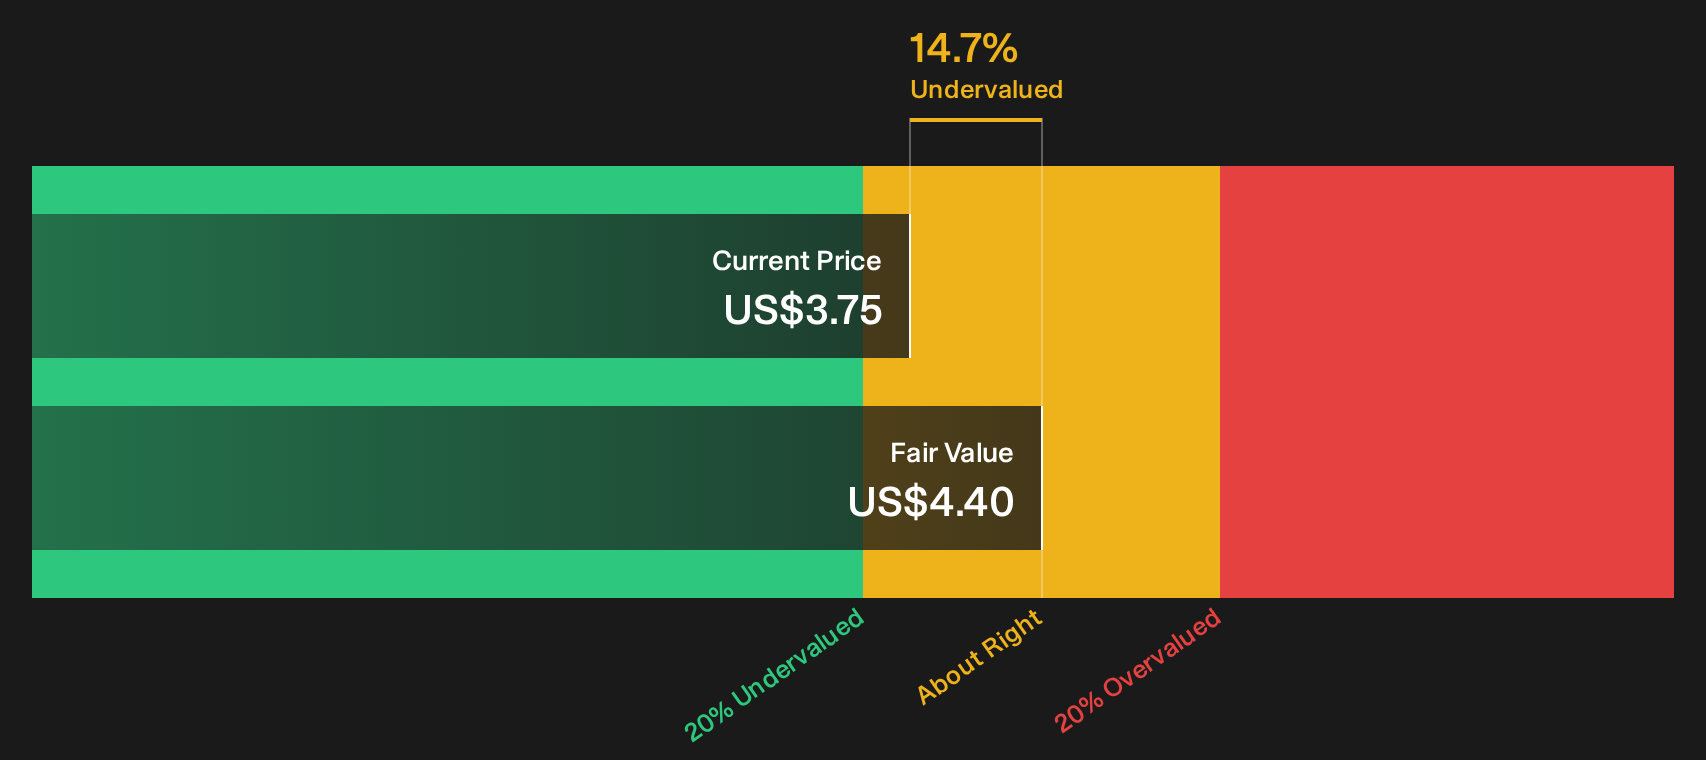
The Discounted Cash Flow (DCF) model here projects what MannKind’s future cash generation could be worth in today’s dollars. The latest twelve month free cash flow is a loss of about $24.1 million, so the model leans on a recovering cash flow profile that moves from current pressure into positive territory over time. On that basis, the 2 Stage Free Cash Flow to Equity framework points to an estimated intrinsic value of about $4.40 per share.
Compared with the current market price, that DCF outcome implies MannKind screens roughly 14.7% undervalued. The recent licensing deal with Rose Pharma on an inhaled GLP-1 helps explain why projected cash flows further out have become more important in the story, even if clinical and regulatory work still needs to clear key milestones first.
On this Discounted Cash Flow view, MannKind stock currently looks undervalued relative to the cash flows the model assigns to it.
Our Discounted Cash Flow (DCF) analysis suggests MannKind is undervalued by 14.7%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Is MannKind a Bargain on Sales?
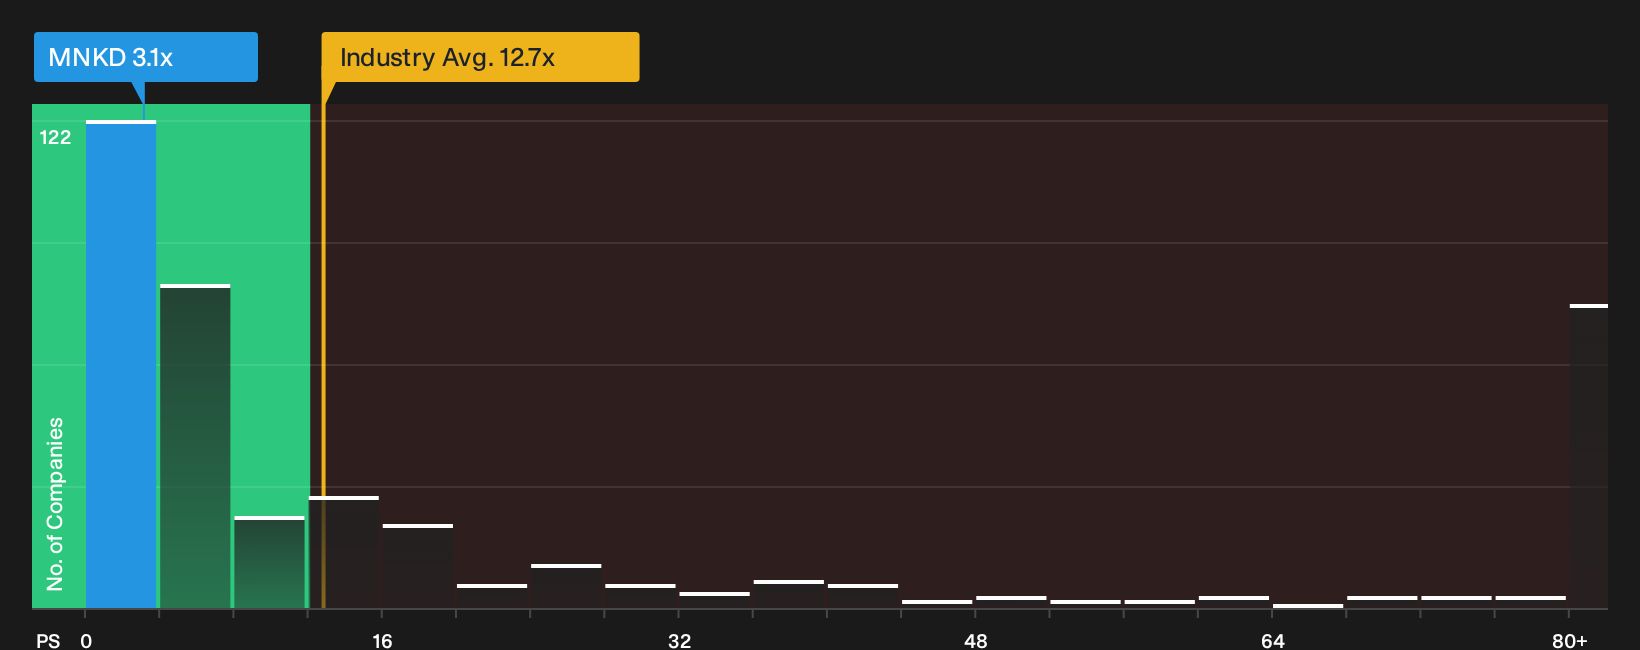
P/S fits MannKind because the business is still loss making and investors are effectively paying for access to its revenue stream rather than current earnings.
The stock trades on a P/S of 3.1x, which sits well below the biotech industry average of 12.7x and the peer group average of 15.1x. The fair P/S ratio for MannKind, based on its size, risk profile and sector, is estimated at 4.8x. That is higher than where the shares trade today, so the current tag implies a discount to what this framework suggests for the company’s revenue base.
On this P/S yardstick, MannKind stock appears undervalued relative to both its industry and the model’s fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The MannKind Narrative: What Would Justify Today's Price?
Narratives for MannKind pick up where the valuation puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than the current quote. All of this is housed on Simply Wall St's Community page. Each narrative sets out a clear, testable framing of MannKind's implied value so you can see how the thesis holds up as new information comes through.
One of the top community narratives on MannKind: 71% undervalued
"The July 26 Furoscix ReadyFlow Autoinjector FDA decision is framed as an underappreciated catalyst that could influence both revenue potential and gross margin trajectory..."
Read one of the top narratives on MannKind
Do you think there's more to the story for MannKind? Head over to our Community to see what others are saying!
The Bottom Line
MannKind screens as undervalued on both the Discounted Cash Flow (DCF) view and simple sales multiples, yet the broader checks still come through as mixed rather than emphatically cheap. That points the decision back to execution on the pipeline and deal portfolio, especially whether inhaled GLP-1 progress and partnered assets can translate into the kind of cash flow profile the models assume. The crux for investors is whether the current discount reflects an overly cautious market or a fair cushion for clinical and regulatory risk that may take time to clear.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com