
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
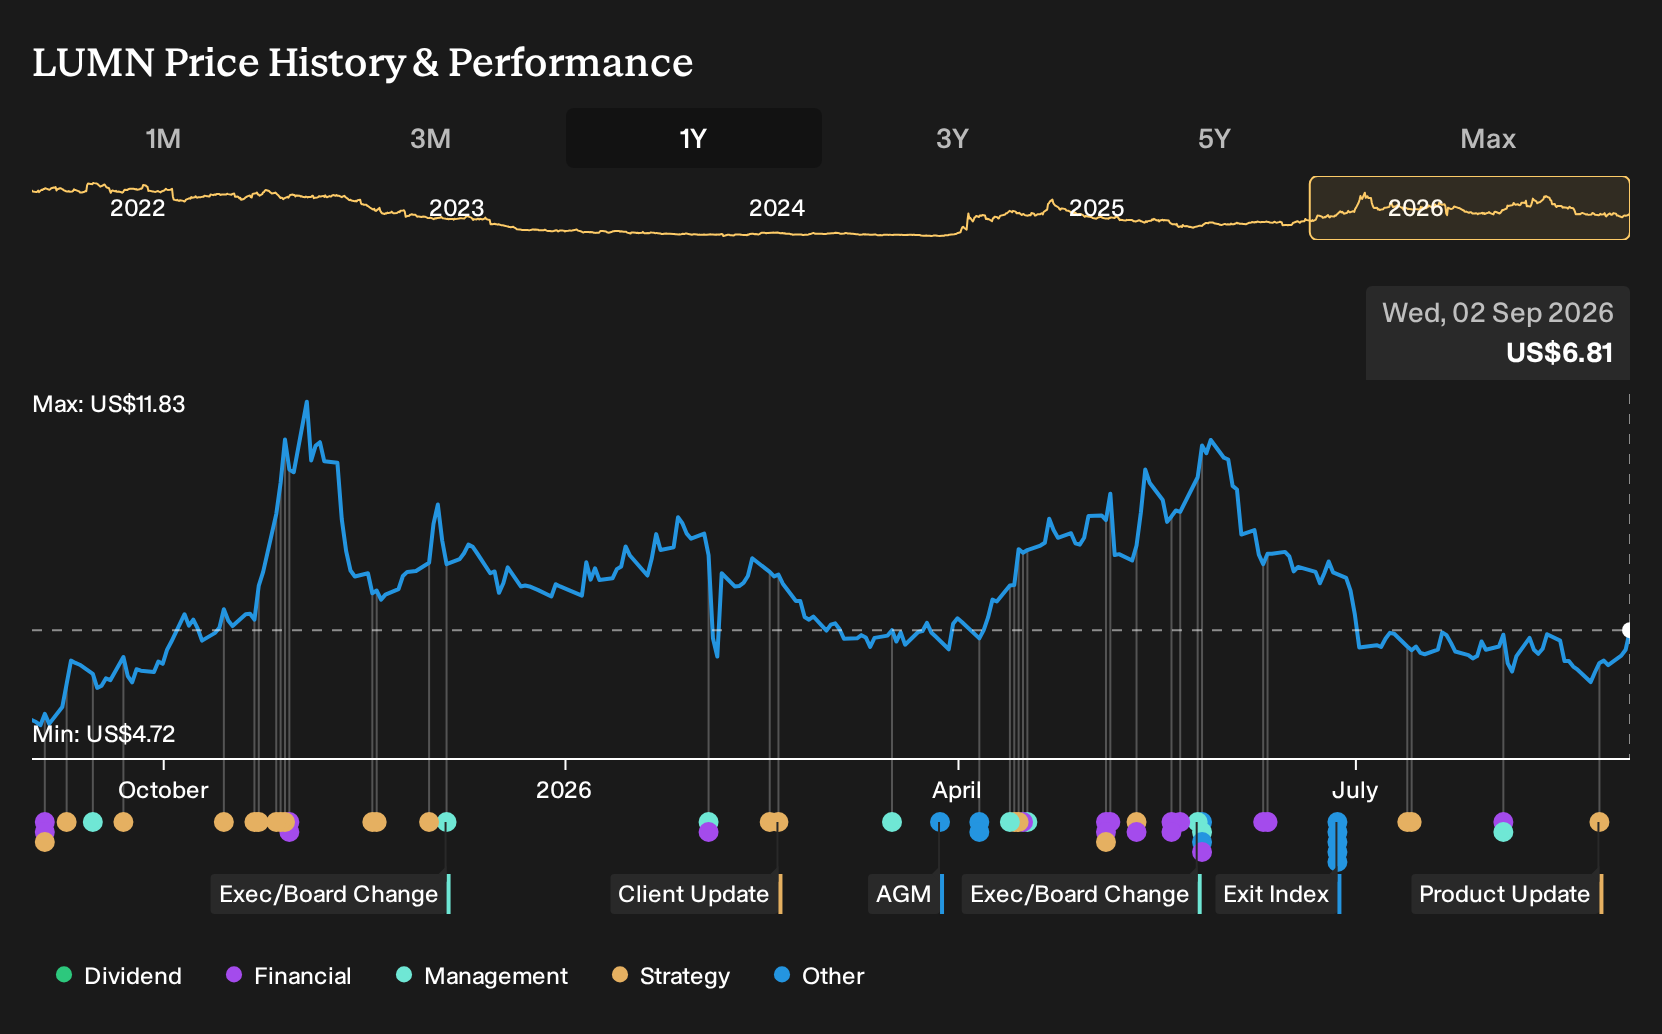
Why Lumen Technologies (LUMN) Is Up 11.8% After Widening Access To Multi-Cloud Gateway Services
- In August 2026, Lumen Technologies expanded access to its Multi-Cloud Gateway service, allowing more than 10 million U.S. business locations, including sites beyond its fiber footprint, to connect to private, high-performance cloud networking through the Lumen Connect portal and APIs.
- This move gives enterprises a single, consistent networking model across dispersed locations and cloud platforms, potentially making Lumen a more integral infrastructure partner for complex hybrid and multi-cloud deployments in sectors like healthcare, finance, and manufacturing.
- Next, we’ll examine how extending Multi-Cloud Gateway beyond Lumen’s network footprint could influence the company’s investment narrative around digital networking.
Find 54 companies with promising cash flow potential yet trading below their fair value.
Lumen Technologies Investment Narrative Recap
To own Lumen Technologies today, you generally need to believe its pivot toward AI-ready, cloud-centric networking can eventually offset pressure from shrinking legacy services and a heavy debt load. The Multi-Cloud Gateway expansion fits that thesis by broadening Lumen’s digital platform reach, but by itself does not clearly change the near term catalyst of stabilizing enterprise revenue or the key risk around ongoing losses and refinancing needs.
This Multi-Cloud Gateway move sits alongside Lumen’s April 2026 launch of AWS Interconnect – Last Mile with Lumen Cloud Interconnect, which gave enterprises private, on demand access to AWS through Lumen Connect. Together, these offerings show how Lumen is trying to deepen its role in multi cloud networking, a potential catalyst if adoption scales fast enough to matter against continued revenue declines in legacy products.
Yet, despite these promising product moves, investors should also weigh the risk that high debt and capital requirements could still limit the company’s ability to fully benefit from them...
Read the full narrative on Lumen Technologies (it's free!)
Lumen Technologies’ narrative projects $10.4 billion revenue and $942.7 million earnings by 2029.
Uncover how Lumen Technologies' forecasts yield a $7.82 fair value, a 15% upside to its current price.
Exploring Other Perspectives
While the new Multi Cloud Gateway access highlights upside for Lumen’s digital networking pivot, the most pessimistic analysts were still assuming revenue would fall to about US$10.1 billion and that losses would persist, reminding you that expectations for long term returns can differ sharply even before this development is reflected in forecasts.
Explore 6 other fair value estimates on Lumen Technologies - why the stock might be worth 36% less than the current price!
The Verdict Is Yours
Don't just follow the ticker - dig into the data and build a conviction that's truly your own.
- A great starting point for your Lumen Technologies research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- Our free Lumen Technologies research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Lumen Technologies' overall financial health at a glance.
Looking For Alternative Opportunities?
Our daily scans reveal stocks with breakout potential. Don't miss this chance:
- AI is about to change healthcare. These 38 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
- Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 29 best rare earth metal stocks of the very few that mine this essential strategic resource.
- Capitalize on the AI infrastructure supercycle with our selection of the 55 best 'picks and shovels' of the AI gold rush converting record-breaking demand into massive cash flow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com